Choosing seguro médico plans for individuals with chronic conditions means looking beyond the monthly premium. A plan that looks affordable can become expensive if your specialist is out of network, your medication requires substantial coinsurance or your regular treatment is excluded. The strongest comparison starts with the care you already use, then checks what happens if your needs increase.
For someone managing diabetes, rheumatoid arthritis, asthma or another ongoing condition, three things deserve priority: access to treatment, predictable costs and protection against a high-cost year. Here is how to evaluate those factors before enrolling.
Start with comprehensive coverage and pre-existing condition protections
ACA-compliant individual major medical plans cannot deny you coverage or charge you more because of a pre-existing condition. They also cannot exclude beneficios de salud esenciales simply because your condition existed before your coverage began. These protections apply to qualifying plans purchased through the Marketplace and outside it.
As HealthCare.gov explains its pre-existing condition protections, coverage for an existing condition begins when your plan takes effect. Sin embargo, that does not mean every doctor, medication or treatment is covered without restrictions. Networks, medical necessity requirements and benefit rules still apply.
Comprehensive coverage includes categories such as outpatient care, hospitalization, prescription drugs, laboratory services and mental health care. Your deducible, copays and coinsurance determine what you pay when using those benefits.
When reviewing seguro médico plans for individuals, distinguish between protection for your diagnosis and coverage for your specific treatment. A plan may cover rheumatoid arthritis care, for example, while requiring prior authorization for a particular biologic medication.
Which coverage options should you consider?
ACA Marketplace and off-Marketplace plans
The ACA Marketplace is a useful starting point because it lets eligible applicants access premium tax credits and other financial assistance. Horario de atención insurers and networks depend on your Código postal, so a plan recommended by someone en another county may not be available to you.
You can also buy ACA-compliant individual coverage directly from an insurer or through a licensed agent outside the Marketplace. Sin embargo, premium tax credits are available only through Marketplace enrollment. Ask whether a quoted policy is ACA-compliant major medical insurance rather than assuming every product labeled “seguro médico” offers the same protections.
Medicaid and Medicare
Medicaid may be an option depending on your state, income and eligibility category. Eligible people can generally enroll throughout the year. State rules and available managed care networks differ, so check your specialists and medications even if the premium is low or zero.
Medicare may be available before age 65 through qualifying disability or certain conditions, including end-stage renal disease. A chronic diagnosis alone does not automatically establish eligibility. If you already qualify for Medicare, compare coverage using Medicare-specific rules rather than treating Marketplace insurance as interchangeable.
Why short-term and limited-benefit policies need caution
Short-term insurance is not a substitute for ACA-compliant coverage when you need ongoing treatment. Depending on the policy and applicable state rules, it may exclude afecciones preexistentes, omit important benefits or impose benefit limits. Fixed-indemnity policies pay specified amounts for certain events rather than covering your full eligible medical bill.
For people comparing seguro médico plans for individuals with recurring care needs, a low advertised premium should prompt a closer review of exclusions, not an assumption of equivalent . Also, the expiration of a short-term policy generally does not create the same Marketplace enrollment rights as losing qualifying comprehensive .
Compare metal tiers without assuming Gold is always best
Bronze, Silver, Gold and Platino describe how a plan shares covered costs across a standard population. They do not rank the quality of doctors or guarantee a particular deducible. Not every tier is available en every location.
| Metal tier | General cost pattern | What to examine for chronic care |
|---|---|---|
| Bronce | Usually primas más bajas and higher cost sharing | Whether recurring treatment creates substantial costs early en the year |
| Silver | Middle-range cost sharing before additional assistance | Quién puede inscribirse for cost-sharing reductions and the plan’s treatment-specific benefits |
| Oro | Usually higher premiums and lower cost sharing | Whether reduced treatment costs outweigh the additional annual premium |
| Platino | Generally the highest premiums and lowest cost sharing | Local availability and whether frequent care justifies the premium |
A Gold plan can work well for someone with regular specialist visits and expensive prescriptions. But an eligible Silver plan with cost-sharing reductions may provide better financial protection. A Bronze plan can sometimes have a competitive annual total, especially when its premium is much lower and its network fits your needs.
When comparing seguro médico plans for individuals, use metal tiers to narrow the search, then examine the actual benefits. Two Silver plans can have different specialist copays, drug deducibles and out-of-pocket limits. HealthCare.gov’s explanation of plan categories provides additional context for these differences.
Calculate annual costs, not just monthly premiums
For ongoing care, a useful starting calculation is:
Expected annual cost = 12 months of premiums + expected cost sharing for covered care.
Then calculate a separate high-use scenario: las primas anuales plus the plan’s dentro de la red out-of-pocket maximum. This shows your exposure for covered, dentro de la red benefits, not an absolute ceiling on everything you might spend. Primas, noncovered services and most out-of-network expenses do not count toward that maximum.
A hypothetical comparison for someone receiving regular treatment
The figures below are illustrative, not actual quotes. Assume both plans cover the same providers and treatments, no premium assistance applies and the expected cost-sharing figures include all anticipated covered, dentro de la red care.
| Cost measure | Plan A | Plan B |
|---|---|---|
| Prima mensual | $390 | $530 |
| Annual premium | $4,680 | $6,360 |
| Expected annual cost sharing | $5,200 | $2,800 |
| Expected annual total | $9,880 | $9,160 |
| In-network out-of-pocket maximum | $8,800 | $6,500 |
| Primas anuales plus that maximum | $13,480 | $12,860 |
Plan B costs $140 more each month but has a lower expected annual total en this example. It also has a lower covered, dentro de la red high-use total. Different treatment needs could change the result.
Use the same assumptions when pricing seguro médico plans for individuals: the same appointments, prescriptions, tests and procedures. Do not add the deducible again if it is already included en your estimados cost sharing. If these terms are unfamiliar, Seguros2All’s guide to premiums, deducibles and other seguro médico basics explains how they fit together.
Check financial assistance before choosing a tier
Premium tax credits can reduce monthly primas del Mercado for eligible applicants. Quién puede inscribirse depends on factors including household income, household size and access to other qualifying . Use the application for your intended coverage year because assistance rules and thresholds can change.
Reducciones de costos compartidos are separate: they lower deducibles, copays, coinsurance and out-of-pocket limits for eligible applicants who enroll en a Silver plan. You generally do not receive these extra savings by choosing Bronze or Gold. Review how cost-sharing reductions work before ruling out Silver .
For fluctuating income, use a reasonable annual estimate and report changes promptly. Advance premium tax credits are reconciled on your federal tax return, so an inaccurate estimate can affect your final tax result.
Financial assistance can change which seguro médico plans for individuals offer the best value. Compare the premium and benefit structure you personally qualify for, not only the plan’s unsubsidized price.
Confirm when you can enroll and when coverage starts
Individual major medical coverage generally requires enrollment during an annual Período de inscripción abierta or a qualifying Período Especial de Inscripción. If you are shopping for 2027 coverage, check the official deadlines for your state and coverage year rather than relying on a previous year’s calendar. Administrados por el estado del Mercados can have different deadlines and effective-date rules.
Losing qualifying job-based coverage, moving under qualifying circumstances or certain household changes may create a Período Especial de Inscripción. A new diagnosis by itself generally does not. HealthCare.gov’s Período Especial de Inscripción guidance explains qualifying situations and possible documentation requirements.
Before ending existing coverage, confirm the new plan’s effective date and any first-premium payment requirement. An enrollment submission is not the same as active .
Timing matters when evaluating seguro médico plans for individuals with scheduled infusions, surgery or frequent prescription refills. Coordinate the transition with your care team so administrative delays do not leave you without a treatment plan.
How to compare seguro médico plans for individuals against your actual care
Verify every important provider and facility
Search the insurer’s directory for the exact plan and network, not just the insurance company’s name. A physician may accept one network from an insurer but not another. Confirm the practice address, specialist and hospital where you receive care.
Ask the provider’s billing office whether it participates en that specific individual-market network. Then confirm with the insurer and keep the date, representative’s name and reference number. Directory entries can be outdated, so checking both sides reduces uncertainty.
Look beyond your primary doctor. For chronic kidney disease, cancer or complex autoimmune conditions, the dialysis center, infusion site, laboratory, imaging facility and medical equipment supplier can matter just as much.
Also review the network model. HMOs commonly require referrals and restrict nonemergency out-of-network . EPOs typically restrict nonemergency out-of-network care, while PPOs may cover it at higher cost. The plan documents control the details, and local availability varies.
Check prescriptions by name, dose and benefit category
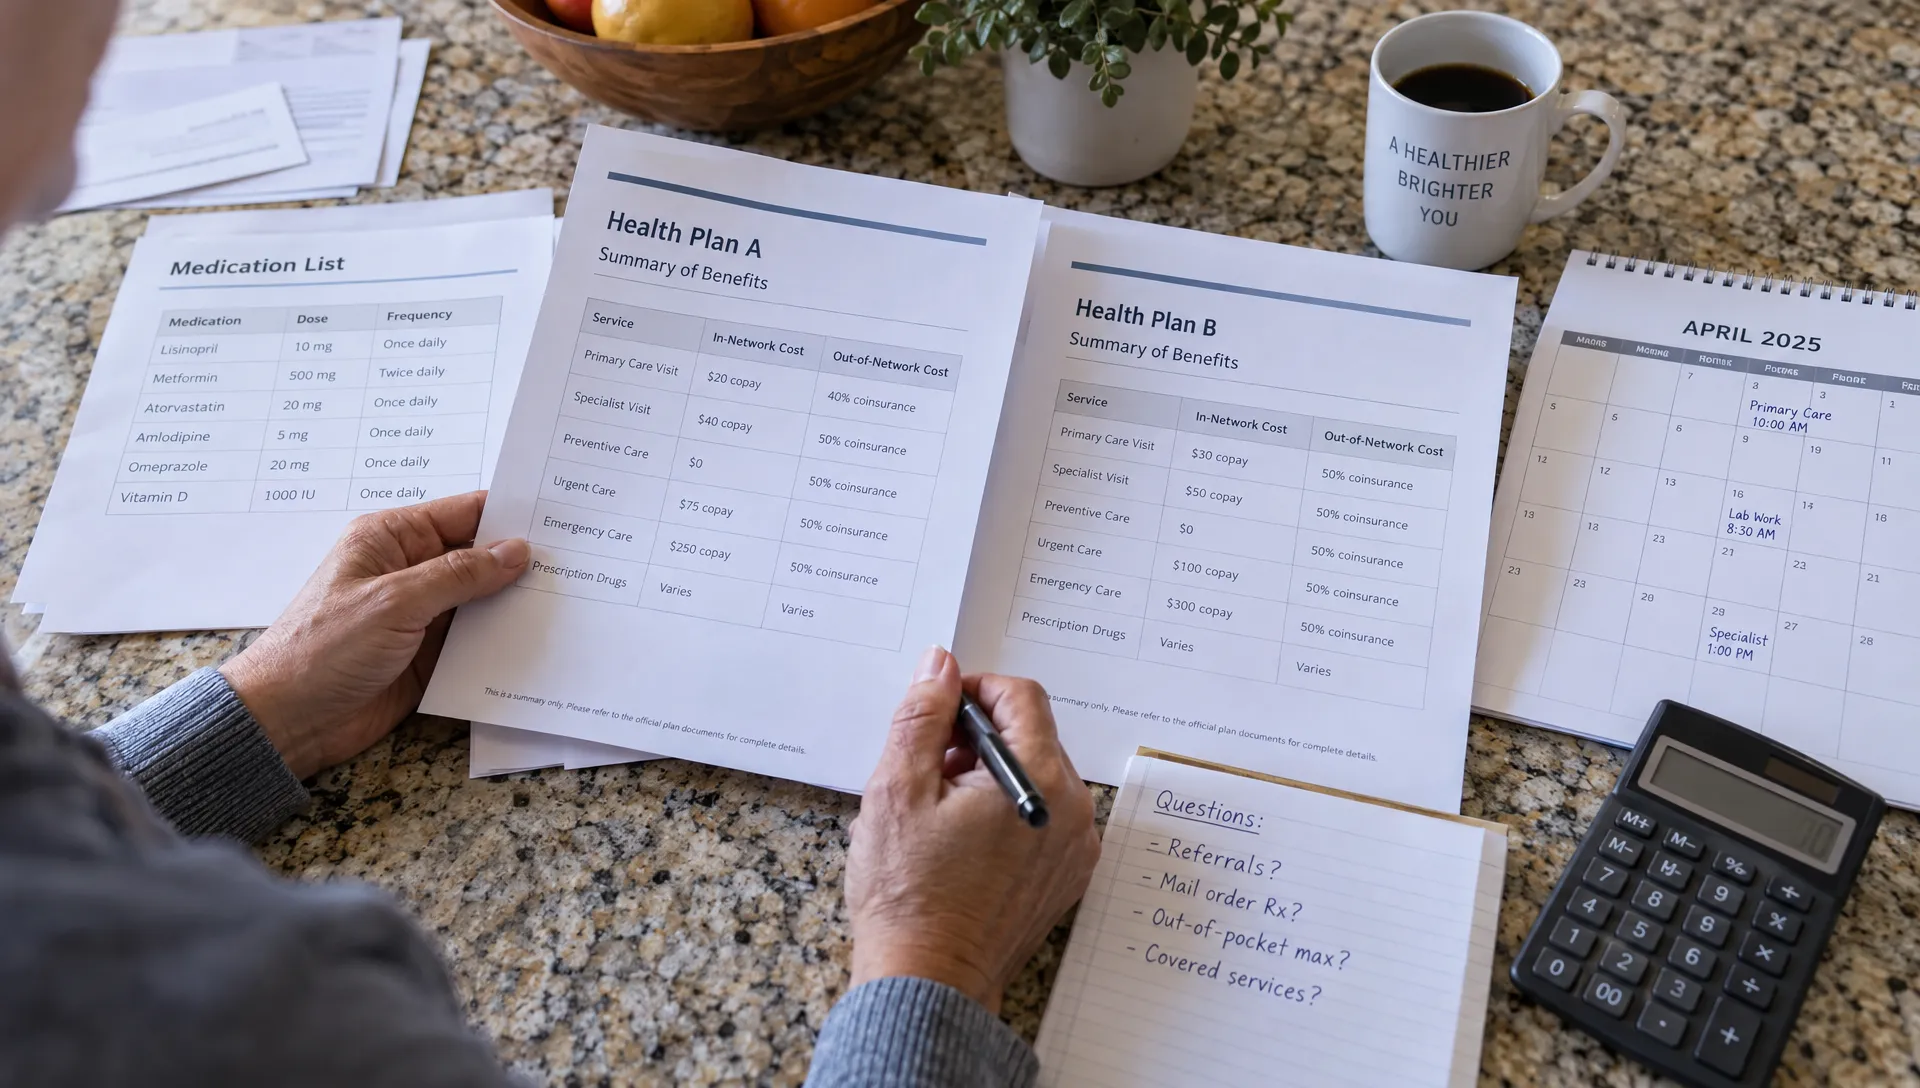
Make a current medication list with the drug name, strength, formulation and refill frequency. Search each plan’s formulary, then confirm the following details with the insurer:
- Cobertura y nivel: Check the exact medication, including whether a generic or biosimilar is preferred.
- Your cost: Determine whether the drug has a copay or coinsurance and whether a deducible applies first.
- Approval rules: Look for prior authorization, step therapy and quantity limits.
- Dispensing requirements: Confirm whether you must use a designated specialty or mail-order pharmacy.
- How treatment is billed: Ask whether an injected or infused drug falls under the medical benefit or pharmacy benefit.
For high-cost specialty medications, a percentage-based coinsurance charge can be more consequential than an office visit copay. Ask for an estimate tied to the exact prescription, not just the tier description.
When reviewing seguro médico plans for individuals, also ask how manufacturer assistance affects your deducible and out-of-pocket accumulation. Do not assume assistance payments will count, since plan rules and applicable state requirements differ.
Review treatment rules and continuity of care
Use the Resumen de beneficios and Cobertura for an initial comparison, then review the detailed policy or Evidencia de cobertura for exclusions and limitations. Check benefits for durable medical equipment, diabetes supplies, rehabilitation, home health services and behavioral health care when relevant.
An existing prior authorization may not carry over to a new insurer. Ask about new authorization requirements, transition prescription fills and any continuity-of-care process before switching. These protections depend on the situation, plan and applicable law; continued access to an out-of-network clinician is not automatic.
If coverage is denied, request the reason en writing and review your appeal rights. Your clinician may need to provide medical records supporting the treatment’s necessity. HealthCare.gov outlines internal appeals and external review options.
Keep copies of the documents you used when choosing . Benefits and formularies can change at renewal, so repeat the review each year even if your condition remains stable.
Preguntas frecuentes
Can I buy individual insurance if I already have diabetes or another chronic condition? Yes. ACA-compliant individual major medical plans cannot deny coverage or increase your premium because of that condition. You still need to meet enrollment requirements and check coverage for your providers, medications and treatments.
Which plan is best for someone who needs frequent care? There is no single best insurer or tier. The strongest seguro médico plans for individuals with frequent care needs combine suitable provider access, appropriate prescription coverage and manageable costo anual totals. An eligible Silver plan with cost-sharing reductions deserves particular attention.
How much does individual seguro médico cost each month? Your premium depends on factors such as location, age, household enrollment and plan choice, with tobacco-related rating permitted en some circumstances. Financial assistance can change your net premium. A chronic condition cannot increase the premium of an ACA-compliant plan.
Will a new plan cover the medication I already take? Not necessarily. Check the exact drug, dose and formulation en the formulary, plus authorization requirements. If it is not covered, ask about the plan’s formulary exception process and discuss alternatives with your prescribing clinician before switching.
Does reaching the deducible mean treatment becomes free? Usually not. Copays or coinsurance may continue until you reach the applicable out-of-pocket maximum. That maximum generally applies to covered, dentro de la red benefits, while premiums and excluded services remain separate expenses.
Compare coverage around your treatment needs
Before requesting quotes, gather your provider names, medication list, expected appointments and current coverage end date. These details make it easier to identify meaningful differences rather than choosing on premium alone.
Seguros2All helps shoppers compare coverage from 50+ aseguradoras, with free, no-commitment quotes, licensed advisor guidance, bilingual support and enrollment application assistance. Plan availability varies by location. Explore individual and family Marketplace coverage through Seguros2All and ask for a comparison built around the care you actually use.