Yes. A Medicare Advantage health plan can require a referral before it covers a visit to a specialist. HMOs usually require referrals, while PPOs generally do not. Your plan’s written rules determine which services need a referral, who can issue it and whether you also need approval from the insurer.
That distinction matters before you schedule a cardiology appointment, begin physical therapy or return to a specialist you have seen for years. A doctor accepting your appointment does not necessarily mean your plan will cover it.
When can your plan require a specialist referral?
Medicare Advantage is an alternative way to receive your Parte A de Medicare and Part B benefits through a Medicare-approved private insurer. Plans can use provider networks and care coordination requirements, including referrals, subject to Medicare rules.
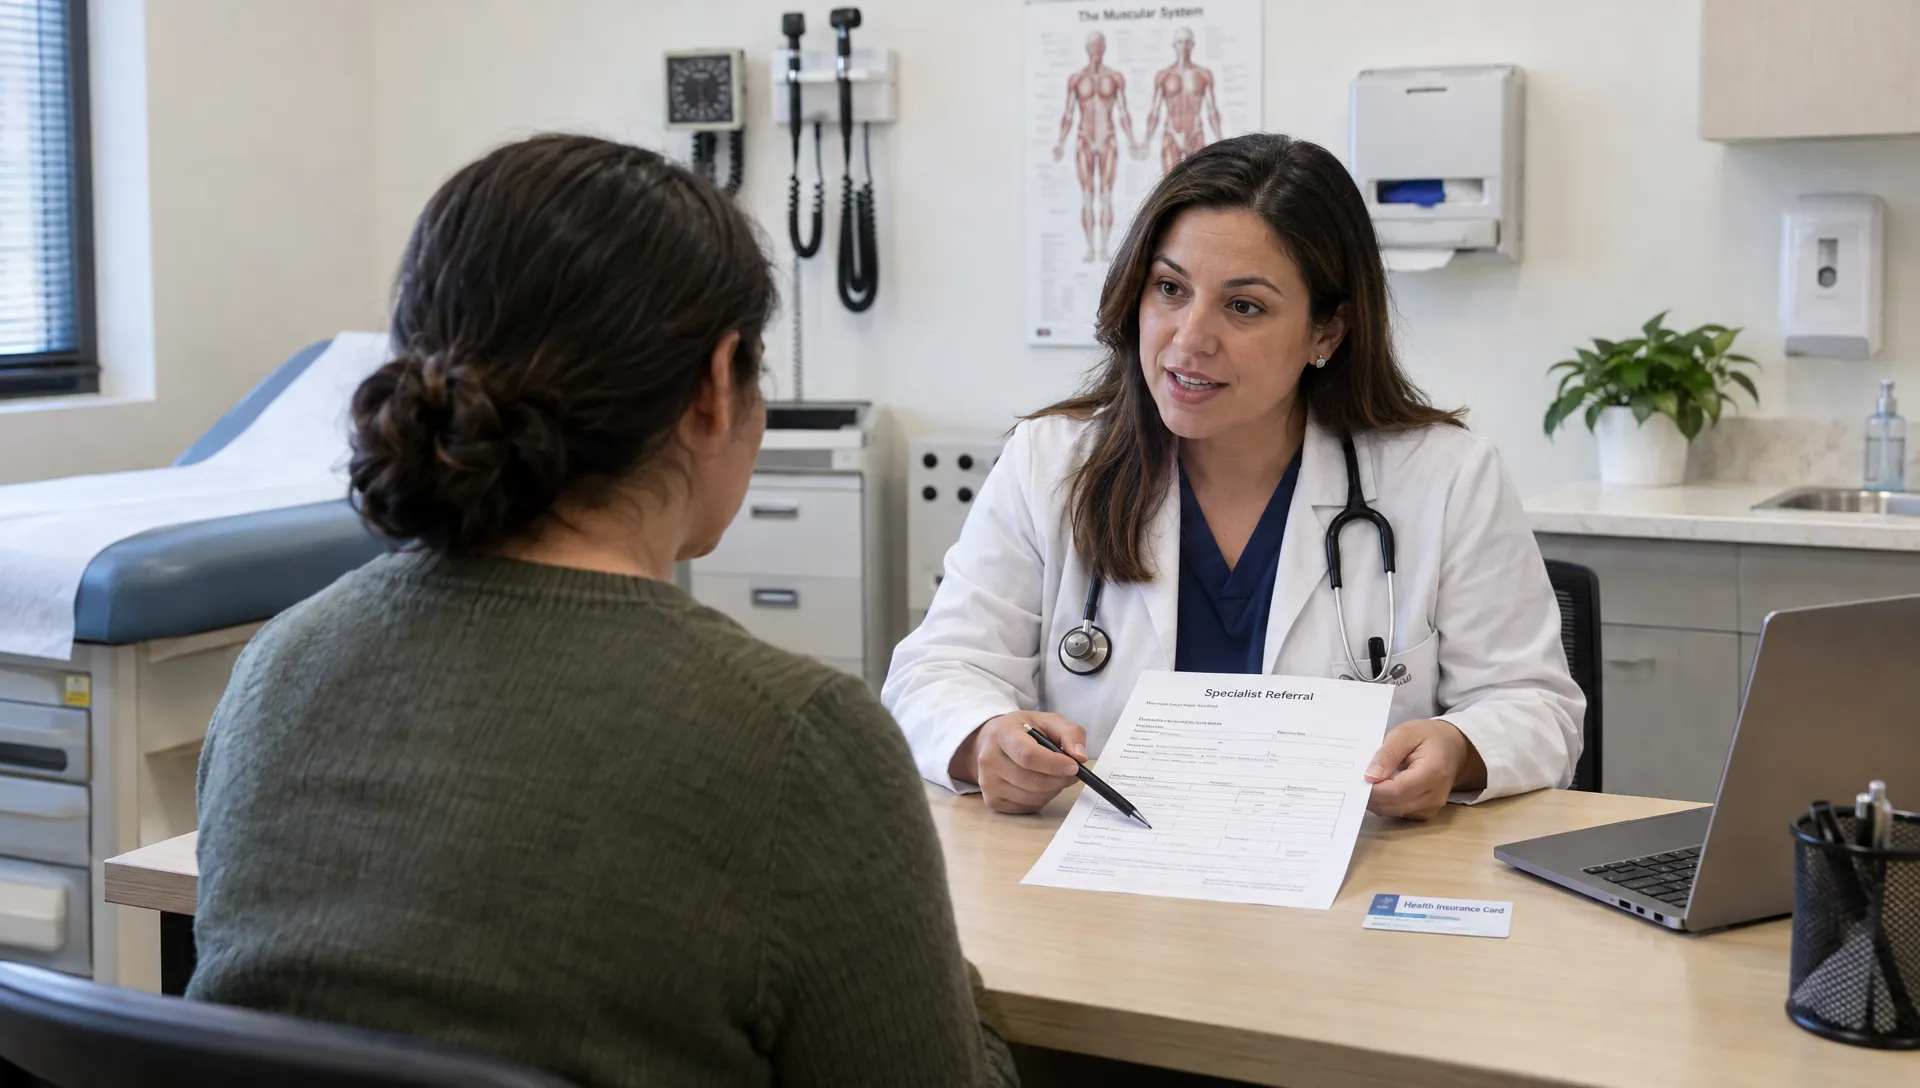
A referral usually comes from your primary care physician, or PCP. It directs you to another provider for an evaluation or treatment. Depending on the plan, it may be submitted electronically rather than handed to you on paper.
A referral requirement en a Medicare Advantage health plan is separate from whether a service is medically necessary or covered. You may need to satisfy several requirements for the same appointment.
Referral, prior authorization and network status are different
A referral is a direction from your PCP to see another provider. When required, it helps establish that you followed the plan’s process for specialist care.
Prior authorization is approval from the insurer before certain services, procedures or medications are covered. A specialist visit may not need authorization, but an MRI ordered during that visit might.
Network status describes whether the provider participates en your specific plan. A referral does not automatically make an out-of-network specialist covered at dentro de la red rates.
Por ejemplo, your PCP might refer you to an orthopedic surgeon, but the surgeon’s office may still need authorization before surgery. The hospital and rehabilitation providers may also have separate network requirements.
Medicare Advantage health plan referral rules by plan type
Medicare explains that HMOs typically require specialist referrals, mientras que PPOs generally let you see specialists without referrals. These are general patterns, not substitutes for checking your plan documents.
| Cobertura type | Usual specialist referral rule | What else to check |
|---|---|---|
| Medicare Advantage HMO | A PCP referral is usually required | Network participation, service exceptions and prior authorization |
| Medicare Advantage HMO-POS | Referrals may be required under the plan’s rules | Which out-of-network services the point-of-service benefit actually covers |
| Medicare Advantage PPO | Referrals generally are not required | Higher out-of-network costs and any authorization requirements |
| Medicare Original | Specialist referrals generally are not required | Whether the provider accepts Medicare and whether the service is covered |
A Special Needs Plan, or SNP, commonly operates as an HMO or PPO. The SNP designation alone does not tell you whether referrals are necessary.
When comparing a Medicare Advantage health plan, look beyond its name or insurance company. Two plans from the same insurer can have different referral rules, networks and costs. Our guide to cómo funcionan los planes Medicare Advantage explains the broader differences among plan types.
Exceptions to ordinary referral requirements
Some services do not follow the usual HMO referral process. Medicare identifies yearly screening mammograms as an example of care that does not require a referral.
Emergency care is also different. Do not delay emergency treatment while trying to obtain a referral or prior authorization. planes Medicare Advantage cover emergency services even outside their networks. Urgently needed care while temporarily outside the service area and out-of-area dialysis also have special coverage protections.
These exceptions do not mean every appointment at an urgent care clinic or every preventive service follows identical rules. Confirm the requirements for nonemergency care with your plan.
How to check the rules before your appointment
Start with your plan’s current Evidencia de cobertura, often called the EOC. Search for “referral,” “specialist,” “primary care” and the service you need. The Resumen de beneficios is useful for comparing costs, but it may not explain every referral condition.
Then call the member services number on your insurance card. A useful question is: “For my exact plan, do I need a PCP referral to see this specialist for this service at this location?”
For a Medicare Advantage health plan that requires referrals, confirm these details before the appointment:
- Who must issue it: Ask whether it must come from your assigned PCP or another authorized clinician.
- What it covers: Confirm the specialist, location, service and number of visits, if limited.
- When it applies: Ask about the effective date, expiration date and any renewal requirements.
- Whether it is on file: Have the specialist’s office confirm receipt before your visit.
- What else is required: Check prior authorization and network status separately.
Write down the date, representative’s name and call reference number. Ask where the rule appears en your coverage documents if the answer conflicts with information from your doctor’s office.
Verify the exact plan, not just the insurance company
A specialist saying “we accept Medicare” does not establish participation en your Medicare Advantage network. Likewise, accepting one plan from an insurer does not mean accepting all of that insurer’s plans.
Check the insurer’s provider directory, then confirm with both the plan and the provider’s billing office. Use the complete plan name and the practice location where you will receive care. A physician may participate at one location but not another.
For an established patient, ask whether a new referral is needed for follow-up visits. An ongoing relationship with a specialist does not automatically waive your plan’s requirements.
What happens if the specialist is out of network?
A referral alone usually does not solve an out-of-network problem. Under an HMO, routine out-of-network care generally is not covered unless an exception or an approved arrangement applies. A PPO typically allows more out-of-network care, but your share of the cost may be higher.
Before using an out-of-network specialist through a Medicare Advantage health plan, ask whether the service is covered, whether approval is required and what you would owe. Do not assume a referral answers all three questions.
If the network cannot provide a medically necessary covered service, ask the plan to arrange appropriate out-of-network care at dentro de la red cost sharing. Get the arrangement confirmed before scheduling nonemergency treatment rather than assuming reimbursement afterward.
If a doctor you already use leaves the network, our guide to what to do when your health plan drops your doctor explains how to verify the change and ask about continuity of care.
What to do if care is delayed or denied
First, identify the actual obstacle. A missing referral, an authorization denial and an out-of-network provider require different solutions. Ask the specialist’s billing office and the insurer which requirement has not been met.
If the referral is missing or incorrect
Contact your PCP’s office to check whether the referral was submitted to the correct specialist and location. Confirm that the patient information and dates are accurate.
Ask whether the appointment should be rescheduled while the issue is resolved, taking your medical needs into account. Do not assume the plan will accept a referral after the visit or pay a bill retroactively.
If the plan refuses coverage
Ask for a formal coverage decision, called an organization determination, if you do not already have one. A verbal scheduling problem is not always a formal denial that you can appeal.
If your Medicare Advantage health plan denies coverage or payment, review the written notice. It should explain the reason and how to appeal. Your treating clinician can help provide records explaining medical necessity or why an available network option cannot meet your needs.
Follow the notice’s filing deadline and keep copies of everything submitted. If waiting for a standard decision could seriously jeopardize your health or ability to regain function, ask whether you qualify for an expedited review. Medicare provides an resumen of appeal rights and procedures.
For independent help understanding Medicare rules, you can also contact your Programa Estatal de Asistencia sobre Seguros de Salud, known as SHIP.
Compare specialist access before choosing a plan
The best referral arrangement depends on how you use care. Someone who regularly sees several specialists may value fewer referral steps. Another person may prefer an HMO whose network includes their existing care team and whose costs fit their budget.
Compare specialist copays, hospital access and the annual medical out-of-pocket limit alongside referral rules. A lower premium does not tell you the total cost of managing a chronic condition.
Before choosing a Medicare Advantage health plan, confirm your current doctors, likely treatment locations and prescription . Also consider travel: emergency coverage away from home does not necessarily include routine specialist appointments en another state.
Plan networks and requirements can change from year to year. Review the Annual Notice of Change and next year’s coverage documents rather than assuming your current arrangements will continue.
When can you change coverage?
Medicare’s annual Período de inscripción abierta runs from 15 de octubre al 7 de diciembre, with changes generally effective January 1. People already enrolled en Medicare Advantage also have a January 1 through March 31 Medicare Advantage Período de inscripción abierta, subject to its rules. Certain circumstances can create a Período Especial de Inscripción.
If you are considering Medicare Original instead, review prescription drug coverage and Medigap eligibility before switching. A right to leave Medicare Advantage does not automatically guarantee a right to buy Medigap without medical underwriting.
Preguntas frecuentes
Can a specialist require a referral even if my PPO does not? Yes. A specialist’s practice may request a clinical referral or medical records before accepting a new patient. That office policy is separate from your insurer’s coverage requirements. Ask whether the request is for clinical review, insurance coverage or both.
Do referrals expire? They can. Your plan may limit a referral by date, number of visits, provider or service. Check those details before follow-up appointments, especially if treatment has been paused or your plan has changed.
Does “no referrals required” mean no prior authorization? No. A Medicare Advantage health plan can allow direct specialist access while requiring authorization for certain tests, treatments or medications. Verify each requirement separately.
Are dental and routine vision referrals handled the same way? Not necessarily. Supplemental dental and vision benefits may use different provider networks and access rules from medical benefits. Check the specific benefit rather than applying your medical specialist rules to every appointment.
Get help comparing referral requirements
Before enrolling, ask for a comparison based on your specialists, prescriptions and expected care, not just the monthly premium.
Seguros2All ofrece free, no-commitment quotes, licensed advisor guidance and bilingual support through enrollment. You can compare available La cobertura de Medicare options with Seguros2All and ask for help reviewing the referral and network requirements that matter to you.