The most affordable family insurance plans do not always put everyone on the same policy. If your children qualify for the Programa de Seguro Médico para Niños (CHIP), they may get low-cost coverage while you buy an adult Marketplace plan or keep employer insurance.
The key is to compare coverage for the whole household without assuming everyone belongs en one program. A child’s CHIP eligibility can affect Marketplace financial help, but it does not automatically prevent eligible parents from receiving their own premium tax credits.
Why children can qualify when parents do not
CHIP covers eligible children en families whose income is too high for Medicaid but who meet their state’s CHIP rules. It generally serves children under 19, although program names and arrangements vary.
Some states operate CHIP separately from Medicaid; others use Medicaid or a combination. A parent’s eligibility is assessed under different rules, so a child can qualify even when an adult does not.
Según HealthCare.gov’s CHIP resumen, benefits include doctor visits, prescriptions, hospital care, dental coverage and vision services. Routine well-child medical and dental visits are free, though other services can have cost sharing.
How affordable family insurance plans can combine CHIP and adult coverage
Start by identifying which person would enroll where. An official eligibility determination matters more than a quote that assumes the whole family qualifies for the same financial help.
| Familiar | Possible coverage | What to confirm |
|---|---|---|
| Child eligible for CHIP | State CHIP coverage | Quién puede inscribirse decision, pediatric network, costs and start date |
| Parent without qualifying employer coverage | Marketplace plan, potentially with financial help | Tax household, projected annual income and subsidy eligibility |
| Parent with employer coverage available | Employer plan or another eligible option | Employee premium, dependent premium and affordability rules |
| Familiar eligible for Medicaid | State Medicaid coverage | Program eligibility, participating providers and effective date |
Por ejemplo, two children might enroll en CHIP while both parents share a Marketplace policy. Alternatively, one parent might use employer coverage while the other buys a Marketplace plan. There is no requirement that everyone use the same insurer.
Separate coverage does mean separate cards, provider networks and billing rules. Keep each person’s plan information available when scheduling appointments.
Keep children en the household calculation
When comparing affordable family insurance plans, distinguish who belongs en your tax household from who needs coverage through a particular plan.
For a typical household of two parents and two dependent children, the Marketplace household size generally remains four even if only the parents need Marketplace insurance. Include household members as the application directs, then identify who is applying for .
Children eligible for CHIP generally cannot receive Marketplace premium tax credits for their own coverage, even if their parents prefer a private plan. Eligible parents may still receive credits toward their own primas del Mercado.
An employer offer can also affect the employee and family members differently. Provide both the employee-only premium and the cost of covering dependents rather than assuming one affordability result applies to everyone.
Check state eligibility before removing children from a policy
There is no single nationwide CHIP income cutoff. State rules, household circumstances and income-counting methods determine eligibility. Marketplace assistance generally uses projected annual household income, while Medicaid y CHIP assessments can use different income periods and rules.
To evaluate affordable family insurance plans accurately, gather the information needed for an official application:
- Household details: Familiars, children’s ages, address and expected tax-filing relationships.
- Income information: Recent earnings, self-employment records and expected changes during the coverage year.
- Existing insurance: Current policies and any employer offers available to household members.
- Care needs: Pediatricians, specialists, medications and ongoing treatment.
CHIP commonly serves uninsured children, and other coverage can affect eligibility. Do not cancel a child’s current insurance just to try to qualify. Ask the state agency how existing coverage affects the application and how to arrange a transition if approved.
Seguros2All’s guide to qualifying for low-cost health coverage explains the broader relationship between household income and coverage assistance. Your state agency makes the actual CHIP eligibility decision.
Compare annual costs, not just monthly premiums
The lowest monthly premium does not necessarily identify the most affordable family insurance plans. Compare what the household is likely to spend over a full year, including the costs of separate adult and child .
Use this calculation: Primas anuales + expected medical and prescription cost sharing = estimados annual household cost.
Cost sharing includes deducibles, copays and coinsurance you expect to pay. Do not add the entire deducible again if those expenses are already included en your estimate.
A hypothetical split-coverage comparison
Suppose two parents qualify for Marketplace assistance and their two children qualify for CHIP. The following numbers are invented examples, not quotes or estimates of typical prices.
| Concepto de costo | Parents on Marketplace, children on CHIP | Everyone on Marketplace |
|---|---|---|
| Combined monthly premiums | $270 | $540 |
| Primas anuales | $3,240 | $6,480 |
| Expected annual medical and prescription cost sharing | $1,550 | $1,800 |
| Estimated annual household cost | $4,790 | $8,280 |
The split option assumes a $240 monthly adult premium and a $30 combined monthly CHIP premium. The all-Marketplace option assumes eligible assistance applies only to the parents, not the CHIP-eligible children.
Actual results depend on your state, income, available insurers and care needs. Some CHIP programs charge no premiums, while others charge premiums or copays. Under federal CHIP rules, total family spending on CHIP premiums and cost sharing cannot exceed 5% of annual family income. That limit does not cap the parents’ separate insurance costs.
Stress-test the expensive year
A useful comparison of affordable family insurance plans also considers a year with surgery, hospitalization or repeated specialist visits.
For the adult plan, review its dentro de la red out-of-pocket maximum for covered services and add las primas anuales. Then account separately for the children’s CHIP premiums and cost sharing, subject to the applicable CHIP limit.
Separate programs do not share one household deducible or out-of-pocket maximum. A parent’s spending under a Marketplace policy does not satisfy a child’s CHIP cost-sharing requirements.
If eligible for Marketplace cost-sharing reductions, compare Silver plans carefully. Those reductions can lower deducibles and other out-of-pocket costs, but they generally require enrollment en a Silver Marketplace plan. A cheaper-premium Bronze plan may cost more when adults need substantial care.
Check pediatric networks and prescriptions before enrolling
A low CHIP premium is less useful if your child’s current specialist does not participate. Likewise, a familiar insurance company name does not guarantee the same network across CHIP, employer coverage and Marketplace products.
Check each child’s pediatrician, preferred hospital, specialists, therapists and pharmacy against the specific CHIP plan. Confirm participation with both the plan and the provider’s billing office. Ask about referrals, prior authorization and any rules for ongoing treatment.
For prescriptions, verify the exact drug, formulation and dosage. A medication can be covered but still require authorization or a trial of another treatment first. Families managing asthma, diabetes or behavioral health conditions should resolve these questions before changing .
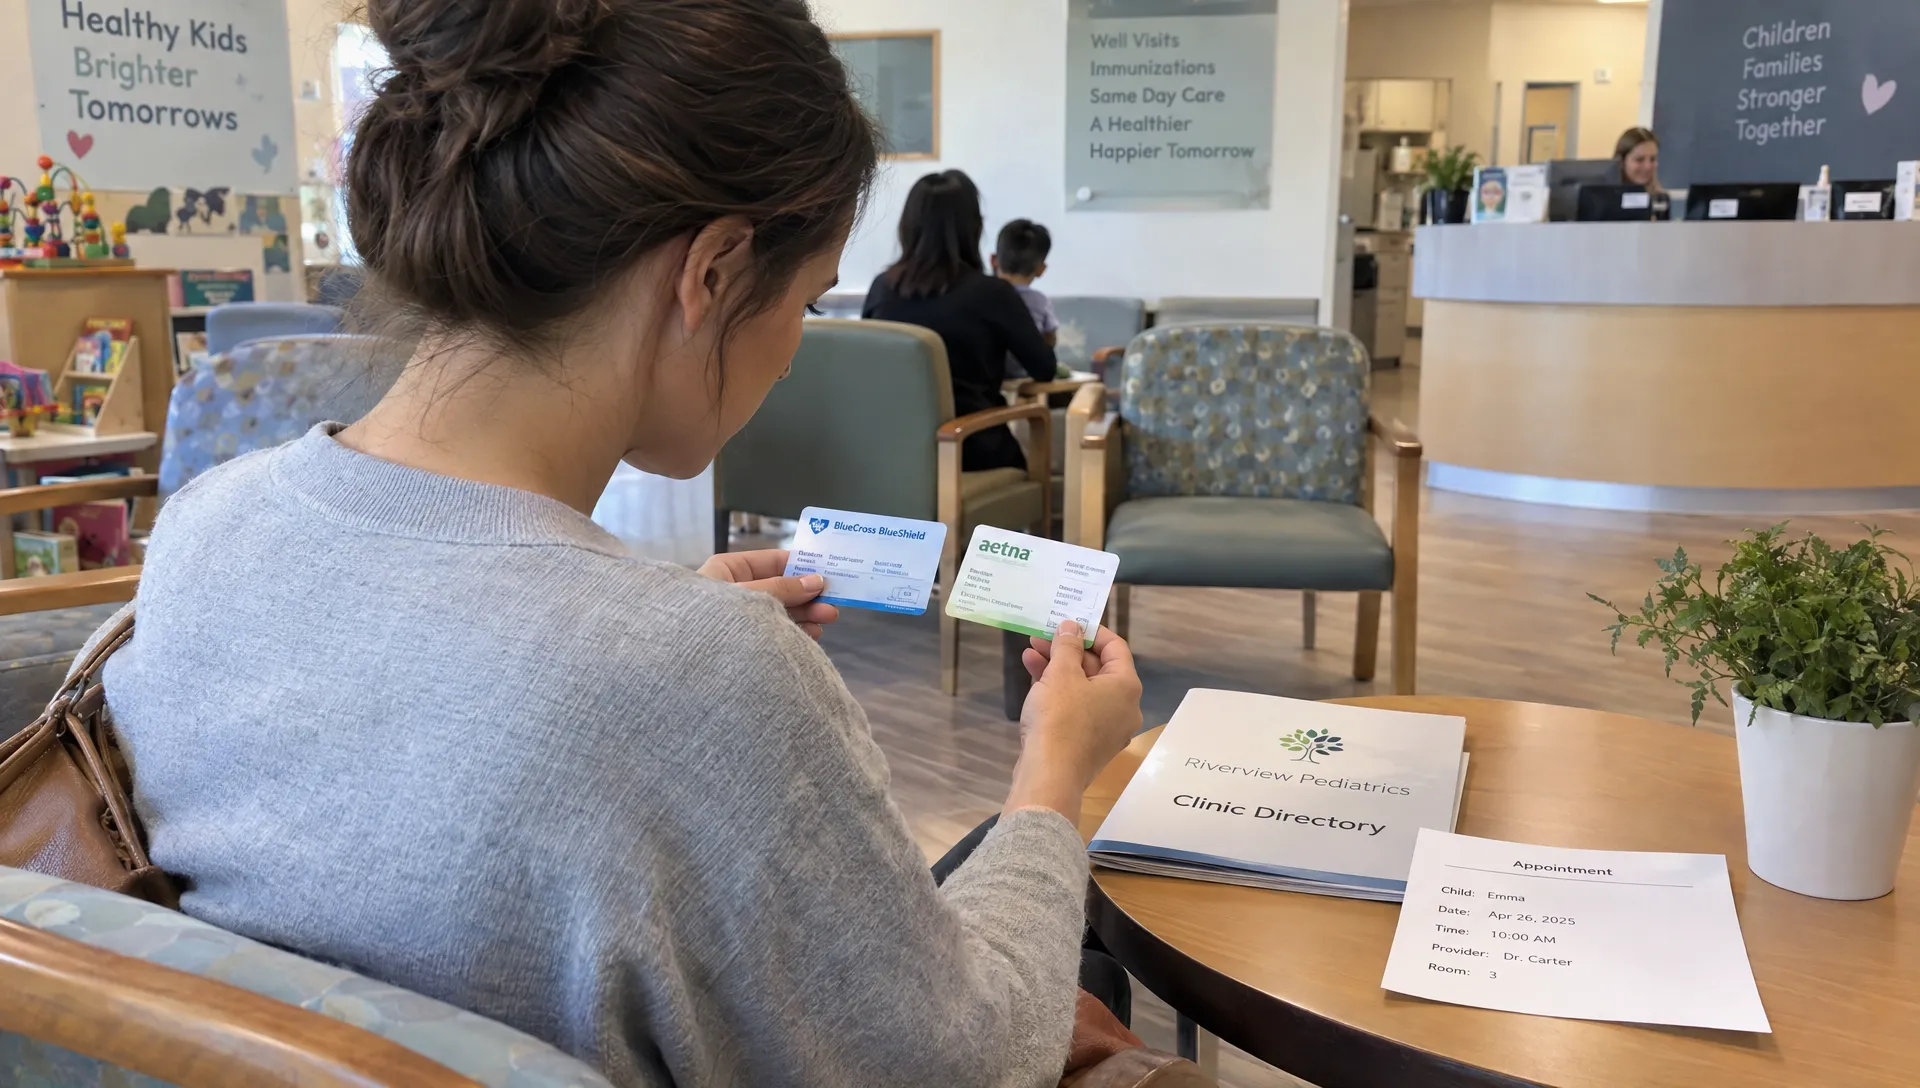
Check adult benefits separately, including optional services. Por ejemplo, if you are considering Kickoff’s nutrition and fitness coaching, ask your insurer and the provider which dietitian services your specific plan covers and whether training has separate charges. Do not assume coverage advertised for some insurance plans applies to your policy or your child’s CHIP benefits.
Prioritize access to necessary care over optional wellness benefits. Quién puede inscribirse follows state and program rules, while primas del Mercado, available insurers and provider networks can also vary by county.
Coordinate applications and effective dates to avoid gaps
Medicaid y CHIP applications are accepted year-round. Parents generally need Marketplace Open Enrollment or a qualifying Período Especial de Inscripción to enroll en Marketplace .
This timing difference matters when arranging affordable family insurance plans across multiple programs. A child’s application does not automatically create an enrollment opportunity for an uninsured parent.
Apply and track each person’s result
A Marketplace application can identify household members who may qualify for Medicaid or CHIP and route their information to the state. You can also apply through your state’s Medicaid or CHIP agency.
A referral is not the same as completed enrollment. Watch for requests for documents, respond by the stated deadline and obtain a final eligibility notice. Record the effective date for every household member.
Before ending existing coverage, ask both programs how to coordinate the change. You want to avoid a coverage gap and avoid receiving Créditos fiscales del Mercado de Seguros Médicos for months when a child is not eligible for them. Confirm any adjustment to the adult policy’s premium after the children leave it.
Verify the current enrollment calendar
For 2027 Marketplace coverage, check the current enrollment dates and deadlines and your state Marketplace’s instructions. State-based Marketplaces may use different calendars, and the enrollment date can affect when coverage begins.
If a child loses Medicaid or CHIP eligibility, that loss may create a Marketplace enrollment opportunity. Review the applicable Período Especial de Inscripción rules promptly rather than assuming the next annual enrollment period is the only option. Voluntarily dropping coverage is not the same as losing eligibility.
Keep split coverage affordable after enrollment
Affordable family insurance plans require follow-through when household circumstances change. Report changes as instructed by each program, especially income changes, a new address, a new employer offer or a change en tax household.
Children under 19 generally receive 12 months of continuous Medicaid or CHIP eligibility, with limited exceptions. That protection does not eliminate renewal requirements or the need to respond to notices. Keep contact information current so renewal requests reach you.
Changes can affect the parents differently. A raise might change Marketplace financial help even while a child remains covered during a continuous eligibility period. Update the Marketplace’s annual income estimate when appropriate to reduce the risk of receiving too much advance premium tax credit.
Also ask the CHIP program how it tracks any required family cost-sharing limit. Save premium records, copay receipts and eligibility notices rather than assuming separate insurers exchange all the information you need.
Preguntas frecuentes
Can children have CHIP while their parents have Marketplace insurance? Yes. Children can qualify for CHIP while eligible parents buy Marketplace coverage, potentially with premium tax credits. Each person’s eligibility is assessed under the relevant program’s rules.
Can I keep CHIP-eligible children on a Marketplace plan instead? You can generally buy Marketplace coverage for them, but children eligible for CHIP usually cannot receive premium tax credits for their own . Confirm eligibility and effective dates before choosing the private option.
How much should family insurance cost each month? There is no reliable national price for your household. When evaluating affordable family insurance plans, compare your actual adult premiums, CHIP charges and expected out-of-pocket spending rather than relying on an advertised family rate.
Will all the children en my household qualify for the same program? Not necessarily. Age and other eligibility factors can produce different results, including Medicaid for one child and CHIP for another. Review each child’s determination rather than treating the household as one coverage decision.
Is short-term insurance a comparable substitute for the parents? Not necessarily. Short-term policies are not equivalent to comprehensive ACA coverage and may have exclusions, benefit limits or medical underwriting. Compare their limitations carefully, not just their premiums.
Compare the adult coverage your family actually needs
Once you understand the children’s CHIP eligibility, request quotes for the adults who still need . Compare premiums, prescriptions, provider access and annual financial risk together.
Seguros2All ofrece free, no-commitment quotes and licensed advisor guidance for individual and family Marketplace coverage. Ask for an adult-coverage comparison that accounts for your children’s CHIP status so you can evaluate affordable family insurance plans without assuming everyone needs the same policy.