If you’re searching for “medicare for family” because you’re approaching retirement, the most important distinction is this: Medicare covers eligible individuals, not an entire family under one policy. Your spouse and children cannot join your Medicare coverage as dependents, even if they previously shared your employer health plan.
That does not mean they have to go uninsured. A spouse may qualify for Medicare independently, while younger family members may need employer coverage, a Marketplace plan, Medicaid or the Children’s Health Insurance Program (CHIP). The goal is to coordinate those options before anyone’s current insurance ends.
The short answer: Medicare does not cover dependents
Unlike many employer health plans, Medicare has no employee-plus-spouse or family enrollment option. Each eligible person enrolls separately and has their own coverage, premiums and cost-sharing responsibilities.
This applies to both Original Medicare and Medicare Advantage. Buying a Medicare Advantage plan does not create dependent coverage, and neither a Part D prescription drug plan nor a Medigap policy can insure your spouse or children under your enrollment.
| Family member | Covered by your Medicare enrollment? | Possible coverage route |
|---|---|---|
| Spouse who qualifies for Medicare | No | Their own Medicare enrollment |
| Spouse who does not qualify | No | Employer insurance, Marketplace coverage or Medicaid |
| Dependent child | No | Employer family coverage, Marketplace coverage, Medicaid or CHIP |
| Adult child with a qualifying condition | No | Their own Medicare eligibility or another coverage option |
The answer to “medicare for family” is therefore separate coverage coordinated around each person’s eligibility, rather than one policy for everyone. The federal government’s guide to getting started with Medicare explains the program’s individual eligibility and enrollment framework.
Can your spouse or children qualify separately?
A spouse may qualify using your work record
A spouse who meets Medicare’s eligibility requirements may qualify for premium-free Part A based on your Medicare-taxed work history, subject to Social Security’s rules. This can matter when one spouse spent years raising children, providing unpaid care or working in jobs without enough qualifying credits of their own.
Using a spouse’s work record is not the same as becoming a dependent on that spouse’s Medicare plan. Your spouse still needs their own enrollment. They may also owe premiums for Part B and any additional coverage they choose.
A younger spouse does not become eligible simply because you turn 65 or enroll. Likewise, a spouse who reaches Medicare eligibility does not have to choose the same coverage arrangement, insurance company or provider network as you.
Children need their own eligibility, not a parent’s Medicare card
Children generally cannot receive Medicare through a parent’s enrollment. However, some people under 65 qualify independently because of disability, amyotrophic lateral sclerosis (ALS) or end-stage renal disease (ESRD).
For many disability-based beneficiaries, Medicare begins after 24 months of qualifying disability benefits. Different timing rules apply to ALS and ESRD. Some children with ESRD can qualify under specific requirements, but this is not general dependent coverage.
When evaluating “medicare for family” for a child with a disability, distinguish between receiving benefits on a parent’s earnings record and being covered under the parent’s insurance. Social Security and Medicare can determine the child’s own eligibility and effective date.
The familiar rule allowing children to remain on many parents’ health plans until age 26 does not apply to Medicare. For alternatives, Insurance 2ALL’s guide to health coverage choices for young adults explains the options beyond Medicare.
Where can family members get coverage instead?
Employer-sponsored insurance
A working spouse’s employer plan may be the simplest way to keep younger family members insured. Check whether it accepts spouses and children, what dependent premiums cost and whether losing other coverage creates a special enrollment opportunity.
If you plan to remain employed after becoming Medicare-eligible, ask your benefits administrator how Medicare coordinates with your existing insurance. Employer size and the reason for Medicare eligibility can affect which coverage pays first.
Also confirm whether enrolling in Medicare or changing your employer election affects dependent coverage. Do not assume your family automatically keeps its current plan when you retire. Request the coverage-end date and available continuation options in writing.
ACA Marketplace coverage
A younger spouse or children may be able to enroll in a plan through HealthCare.gov or their state’s Marketplace. Losing qualifying job-based insurance generally creates a Special Enrollment Period, usually extending 60 days before and 60 days after the loss. Verify the deadline and effective date for your circumstances.
For many households seeking “medicare for family,” the practical arrangement is Medicare for one adult and Marketplace coverage for the remaining family members.
Marketplace applications generally need information about the tax household, including a spouse who already has Medicare, even when that spouse is not applying for Marketplace coverage. Household income and other eligibility factors affect potential financial assistance.
Eligibility for premium-free Medicare Part A generally makes that person ineligible for Marketplace premium tax credits. That does not automatically eliminate assistance for eligible family members. HealthCare.gov’s Medicare guidance explains how these coverage systems interact.
Medicaid and CHIP
Medicaid may provide coverage for eligible adults and children, while CHIP covers eligible children in families that meet their state’s program rules. Income limits and other requirements vary by state and eligibility category.
Family members can qualify for different programs within the same household. For example, one parent might have Medicare, another might have employer insurance and a child might qualify for CHIP. Medicaid and CHIP applications are available year-round, rather than only during an annual enrollment period.
COBRA or other continuation coverage
If eligible dependents lose employer coverage, COBRA or state continuation coverage may offer a temporary bridge. Availability, duration and cost depend on the employer plan and the event causing the loss.
Compare the full continuation premium with other available options before choosing it. Your Medicare enrollment alone does not necessarily give every dependent a COBRA right; a qualifying event and coverage loss must meet the applicable rules.
How to plan “medicare for family” across separate policies
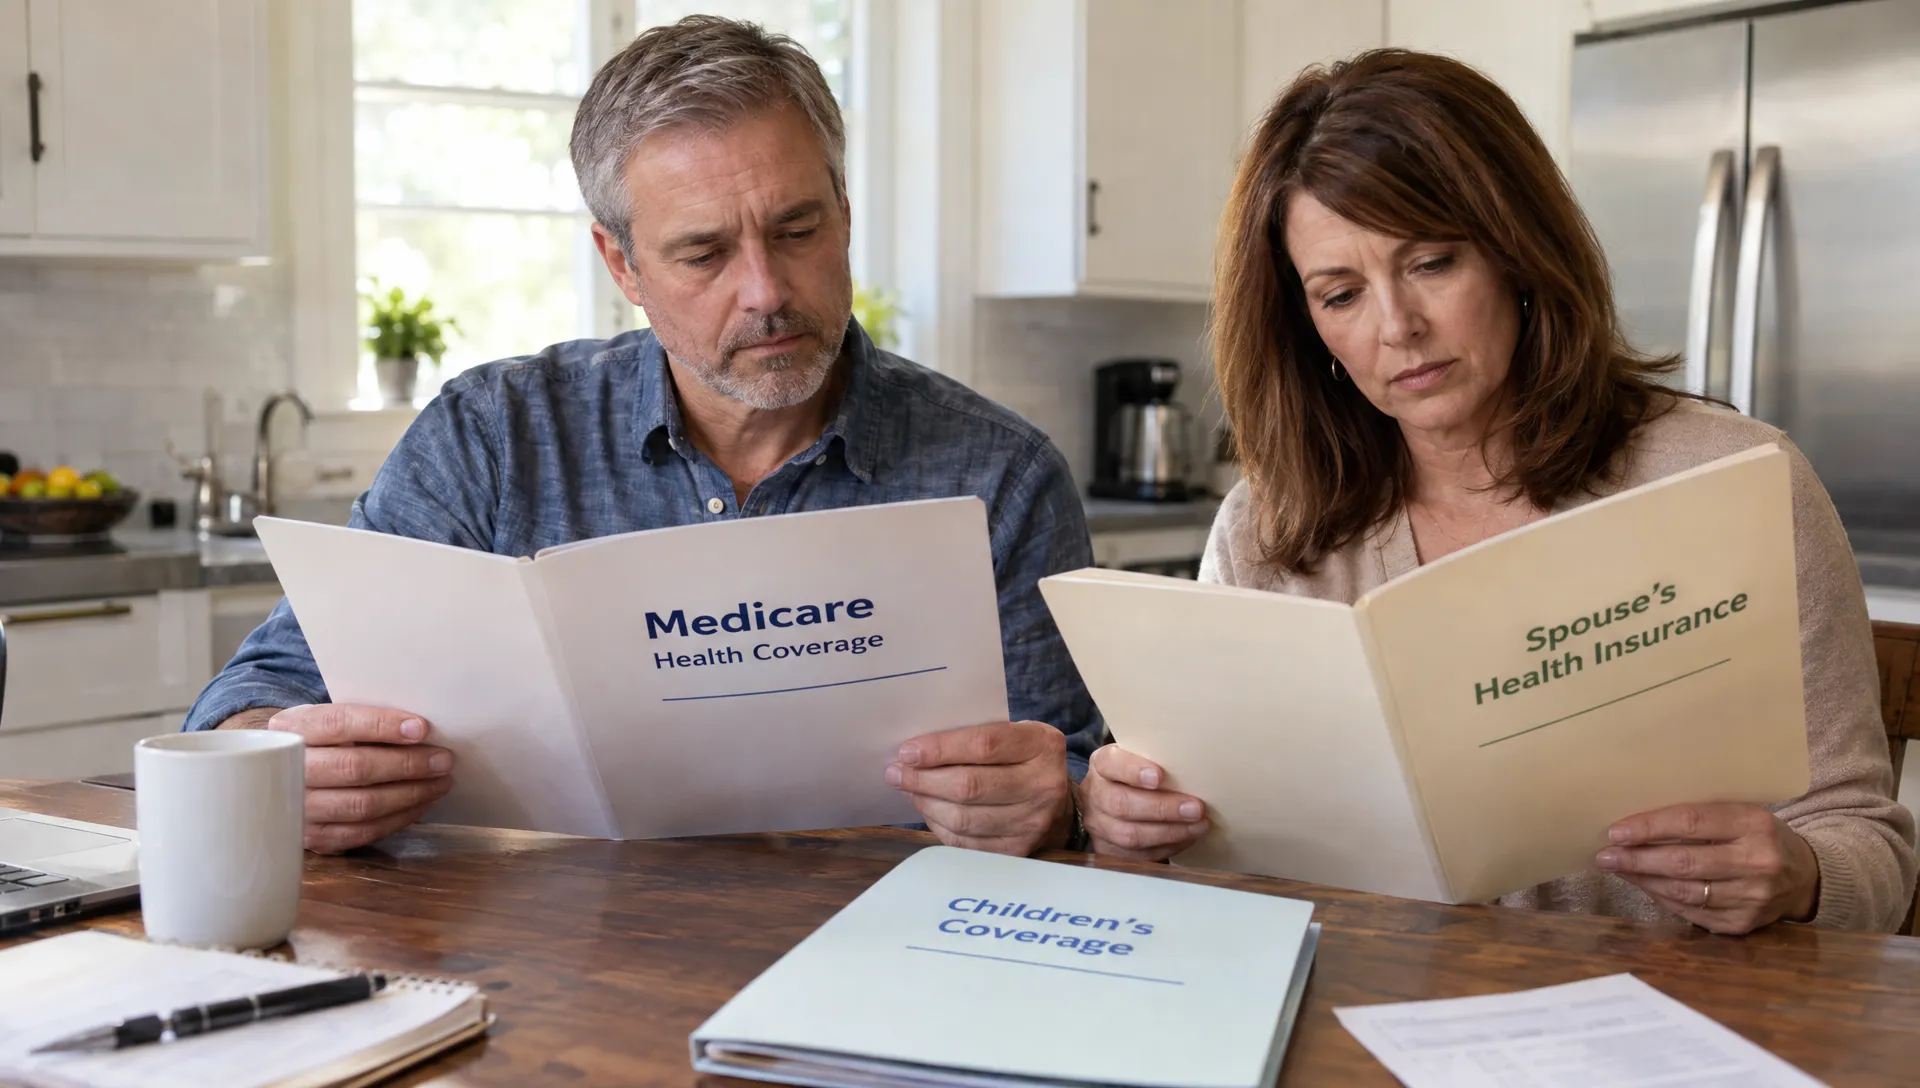
Start with a person-by-person coverage map. Record each family member’s current insurer, eligibility for replacement coverage and the date any existing coverage will end. This is more useful than searching for a single family Medicare product that does not exist.
Before retirement or a coverage change, confirm these points:
- Your enrollment timing: Identify when your Medicare coverage should begin and whether delaying any part is appropriate.
- Your family’s coverage end date: Ask whether dependent insurance ends on your last workday, at month-end or on another date.
- Each person’s enrollment opportunity: Check employer-plan deadlines, Marketplace eligibility and any continuation rights.
- Replacement coverage details: Verify doctors, prescriptions, premiums and the actual effective date before canceling existing insurance.
Coordinating “medicare for family” coverage requires matching these dates, not simply submitting everyone’s applications at the same time.
Your Medicare Initial Enrollment Period generally lasts seven months around your 65th birthday. Eligible people covered through their own or a spouse’s current employment may have a Part B Special Enrollment Period. COBRA and retiree coverage do not count as current-employment coverage for that purpose, so do not assume they let you delay Part B without consequences.
Budget for the household, not just one premium
Add up separate coverage costs
A low Medicare premium does not tell you what your whole family will spend. Build a household estimate that includes each person’s premiums, deductibles, prescription costs and likely copayments or coinsurance.
Keep the plans’ limits separate. Spending under your Medicare coverage generally does not count toward your spouse’s Marketplace deductible or your child’s employer-plan deductible. Original Medicare also has no annual out-of-pocket limit for Part A and Part B services unless other coverage helps protect you.
When budgeting for “medicare for family,” compare the combined cost of the separate policies rather than treating a $0 Medicare Advantage plan premium as a $0 household insurance bill. You generally still pay your Part B premium with Medicare Advantage.
Insurance 2ALL’s explanation of Medicare costs you may still pay can help you identify expenses beyond the advertised premium. Avoid comparing plans on price alone if doing so means losing access to essential doctors or medications.
Recheck coverage if retirement includes a move
Housing and insurance decisions often happen together during retirement. If you’re comparing manufactured homes in San Antonio as part of a relocation, include health coverage costs and access to care in your household budget before committing to the move.
Medicare Advantage and Marketplace plan availability can change with your address, and provider networks may differ. A move can create an enrollment opportunity when applicable requirements are met, but it does not automatically make a spouse or child eligible for Medicare.
Check the proposed location against each family member’s doctors, hospitals and pharmacies. Contact the relevant insurer or Marketplace to confirm whether a plan change is needed and when replacement coverage can start.
Frequently asked questions
Can I add my spouse to my Medicare Advantage plan? No. Medicare Advantage enrollment is individual. Your spouse must qualify for Medicare independently and enroll in their own plan. Even when both spouses choose the same insurer, they have separate policies and cost-sharing responsibilities.
Is there a “medicare for family” plan with one shared premium? No. Medicare does not offer family policies or shared dependent coverage. An eligible couple can both have Medicare, but each person has their own enrollment and applicable premiums. Other family members need coverage through a separate eligible source.
Can my spouse get Medicare if they never worked? Possibly. A spouse who meets the applicable eligibility requirements may qualify for premium-free Part A using your work record. Social Security determines eligibility. This does not make a younger spouse eligible solely because you have Medicare, and other premiums may still apply.
Will my family lose Marketplace savings when I enroll in Medicare? Not automatically. Your Medicare eligibility can change your own eligibility for financial assistance, while other household members may remain eligible. Update the Marketplace application to reflect the change and keep household and income information accurate.
Should both spouses choose the same Medicare coverage? Not necessarily. Different doctors, medications and healthcare needs may make different options appropriate. Compare each person’s coverage separately, then assess the combined household cost.
Compare coverage for each family member
Before changing insurance, identify who qualifies for Medicare, who needs another coverage source and when each policy should begin. Keep existing coverage in place until you have confirmed how and when replacement coverage takes effect.
Insurance 2ALL offers free, no-commitment quotes, access to options from 50+ carriers and guidance from licensed advisors. Bilingual support and enrollment application assistance can help you compare available Medicare and health insurance choices for the people in your household.