A letter saying your health plan will no longer include your doctor can threaten more than a familiar relationship. It may interrupt prescription refills, specialist visits or treatment you have already scheduled. But losing a doctor from the network does not necessarily mean you must stop seeing them immediately, and it does not mean your insurance coverage has ended.
Start by confirming the change, checking whether you qualify for continued in-network care and protecting upcoming appointments. Switching insurance may be an option, but it is not always available right away or necessary.
The right next step depends on your coverage type, treatment needs and the date the network change takes effect. Here is how to work through those questions without creating an avoidable gap in care.
Confirm exactly what changed
Sometimes a doctor leaves an insurer’s network entirely. In other cases, only a particular office location, medical group or network contract changes. A hospital may remain in-network even when an individual physician does not, or the reverse may happen.
Ask your health plan to verify the doctor’s status under your exact plan and network, not just the insurance company’s name. Then contact the doctor’s billing or contracting office separately. “We accept that insurance” is not the same as confirming in-network participation.
Have your member ID, the doctor’s full name, office address and National Provider Identifier, if available, ready. Ask both offices:
- What is the last date this doctor will be in-network for my specific coverage?
- Does the change affect every office location and affiliated medical group?
- Will scheduled visits or procedures occur before or after the termination date?
- Is the departure final, or are contract negotiations continuing?
Save the termination notice, directory screenshots and written responses. Record call dates and reference numbers. Use the member-services number on your insurance card or the authenticated member portal, especially when similarly named plans operate in different states.
If the two offices disagree, request a three-way call. Do not rely on a statement that negotiations will “probably” succeed when deciding whether to keep an expensive procedure scheduled.
Check whether continuity-of-care protections apply
If your health plan loses its contract with a treating provider, certain patients may qualify to continue treatment temporarily under in-network terms. This is commonly called continuity of care.
Federal continuity-of-care law establishes protections for qualifying patients in many employer-sponsored and individual insurance plans. Medicare and Medicaid have their own requirements, and state laws may provide additional protections.
Who may qualify?
Federal protections focus on a “continuing care patient,” not everyone who prefers to keep a particular physician. Qualifying circumstances include:
- Receiving treatment for a serious and complex condition.
- Undergoing institutional or inpatient care.
- Being scheduled for nonelective surgery, including related postoperative care.
- Receiving treatment for pregnancy.
- Having a terminal illness and receiving treatment for it.
For eligible patients, continued care can generally last up to 90 days from the plan’s notice, or until the person no longer qualifies as a continuing care patient, whichever comes first. It preserves applicable in-network treatment terms rather than making care free.
These protections have exceptions, including certain contract terminations involving fraud or failure to meet applicable quality standards. They also cannot make a retiring or unavailable physician keep practicing.
How to request continued treatment
Contact member services and ask specifically for a continuity-of-care request following provider network termination. Some insurers use a related term, such as transition of care.
Ask for the eligibility criteria, submission deadline and required medical documentation. Your physician’s office can help explain why interrupting treatment would be unsafe or disruptive.
Request written confirmation identifying the approved provider, covered services, applicable cost sharing and expiration date. Confirm how existing authorizations will be handled. An authorization for a procedure does not, by itself, guarantee in-network pricing after the provider leaves.
Protect upcoming appointments from unexpected costs
Before keeping a visit after the termination date, ask your health plan what you would owe under each available arrangement: approved continuity of care, an out-of-network benefit or a separately negotiated exception.
The financial difference can be substantial. A PPO may cover some out-of-network services, but a separate deductible, higher coinsurance and balance billing can still apply. HMO and EPO plans often do not cover routine out-of-network care unless an exception applies.
| Situation | What to confirm before treatment |
|---|---|
| Visit occurs before the network termination | The doctor and service remain in-network on the actual treatment date |
| Continuity of care is approved | Which services are included and when approval expires |
| You use an out-of-network benefit | Deductible, coinsurance, allowed amount and possible balance bill |
| No suitable in-network specialist is available | Whether a network-gap exception or single-case agreement is possible |
| Surgery involves several providers | Network status of the facility and clinicians, plus applicable surprise-billing protections |
A network-gap exception asks the insurer to cover an outside provider because an appropriate network option is unavailable. A single-case agreement can establish terms for a particular patient’s care. Neither is guaranteed, so obtain approval before nonurgent treatment.
For help interpreting the difference between a deductible, coinsurance and network restrictions, review this guide to understanding your health coverage.
Do not delay emergency care to resolve a network dispute. Emergency coverage and surprise-billing protections have separate rules; they should not be treated as permission to use any out-of-network doctor for routine appointments.
Challenge incorrect information or a denial
If your health plan denies continued care, request the decision and its reasoning in writing. Ask whether the denial concerns medical eligibility, a missed deadline, missing documentation or an excluded circumstance. The response determines what evidence will help.
Submit an appeal using the instructions and deadlines in the denial notice. Include the termination letter, relevant treatment records and a clinician’s explanation of the risks of interruption. If waiting for a standard decision could seriously jeopardize your health or recovery, ask whether an expedited review applies.
A directory error presents a different issue. For applicable private coverage, federal rules can protect patients who relied on certain incorrect network information from the insurer. CMS explains consumers’ medical-billing rights, including protections related to inaccurate provider directories.
Preserve a dated screenshot and any written confirmation that the doctor was in-network. If a claim has already processed incorrectly, request a claim review or reprocessing based on that evidence. Do not assume the bill is correct simply because the provider sent it.
For unresolved problems, the right regulator depends on the coverage. A state insurance department generally handles fully insured policies. For many private-employer self-funded plans, the U.S. Department of Labor’s Employee Benefits Security Administration is the appropriate contact. Medicare and Medicaid members should use their program’s complaint and appeal channels.
Arrange a handoff before temporary coverage ends
Whether you stay with your health plan or eventually change coverage, build a transition plan while the current doctor is still available. A 90-day continuation period can pass quickly when specialists have long appointment waits.
Ask the current clinician to identify which parts of treatment cannot safely wait. Request a concise transfer summary covering diagnoses, recent test results, medication history and the next recommended steps. Have records sent securely to the receiving practice and obtain copies for yourself when useful.
For prescriptions, confirm how many refills remain and whether the new clinician will need an appointment before prescribing. Ask about prior authorization, specialty-pharmacy requirements and any monitoring needed to continue treatment. Do not change doses or stop medication without clinical guidance.
The insurer should help identify participating alternatives. Verify each proposed clinician’s network status, acceptance of new patients and earliest appointment. A name in a directory is not enough if the office cannot provide the care you need within an appropriate timeframe.
If no suitable appointment is available, document the offices contacted and their responses. That record can support a request for additional help or a network exception. Where referrals are required, arrange a new referral rather than assuming the old one transfers automatically.
Find out whether you can switch coverage now
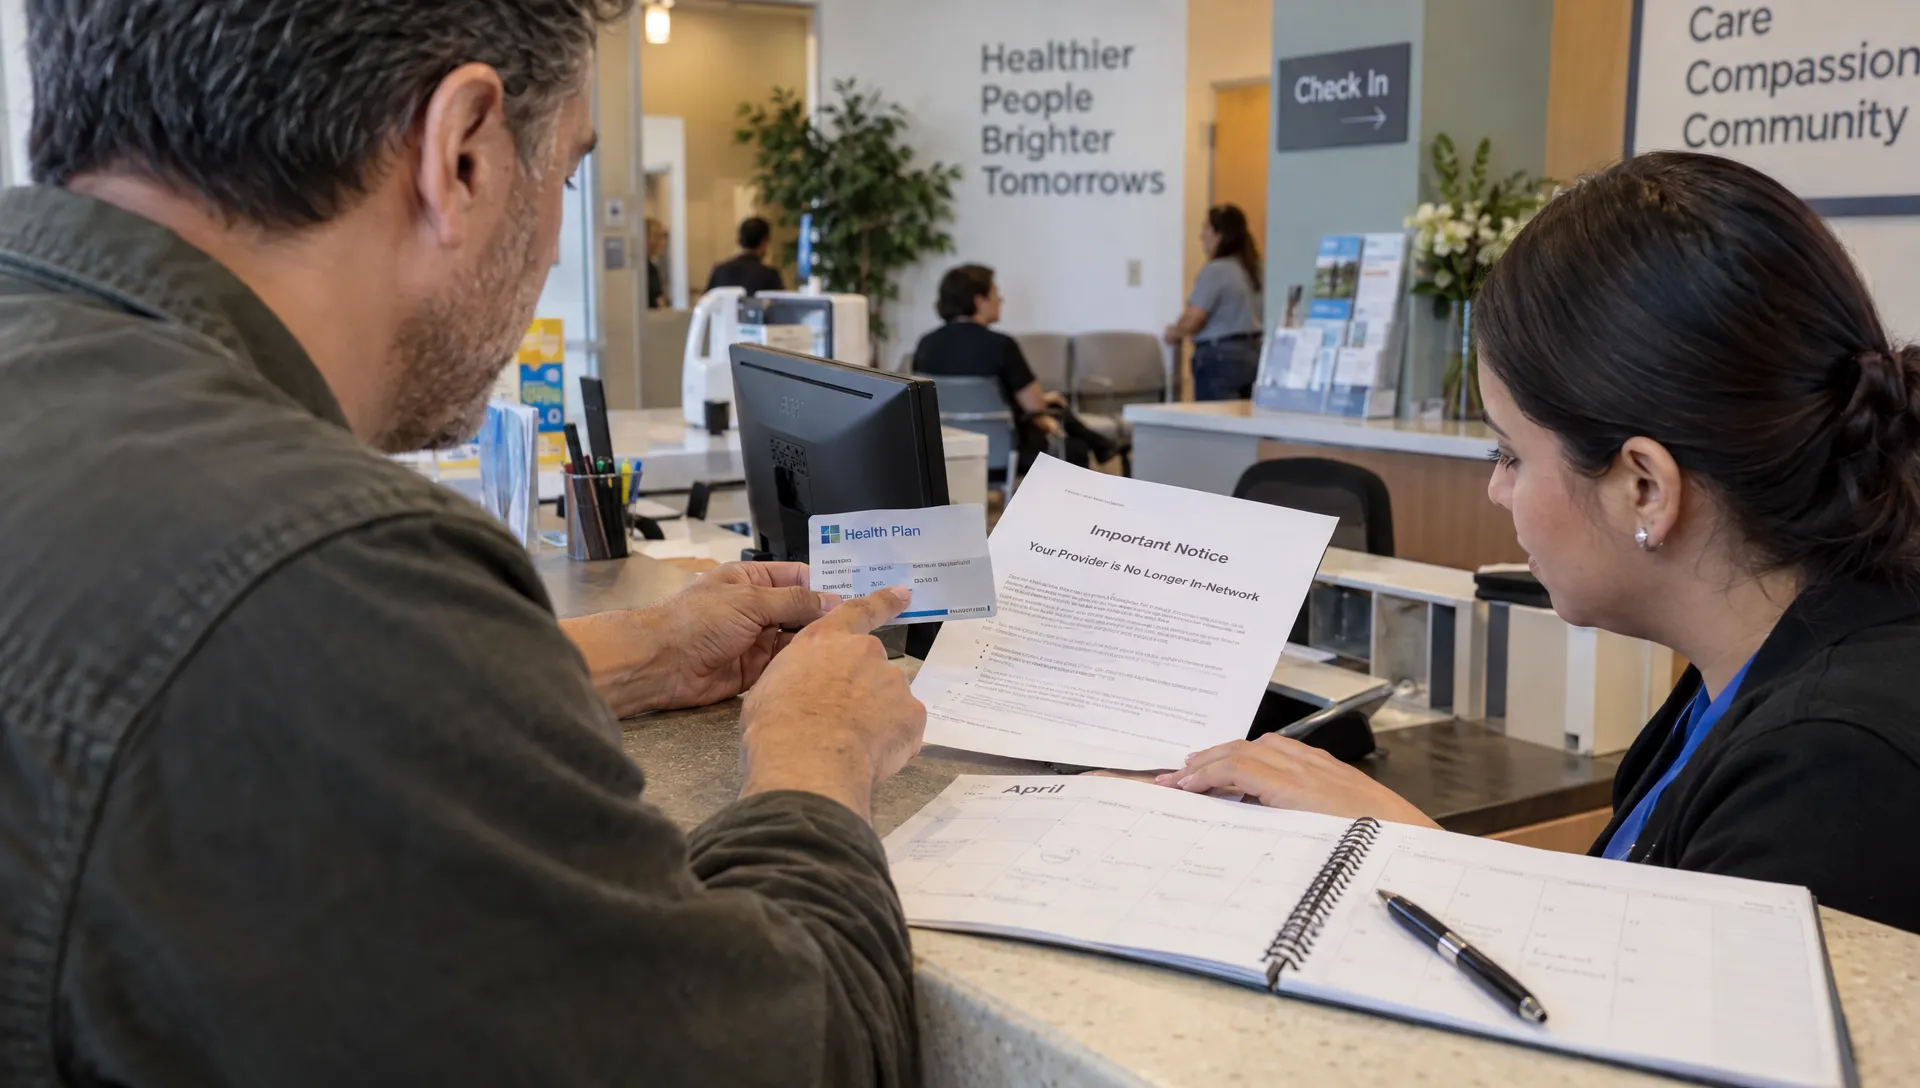
Losing access to a physician is not the same as losing insurance. A doctor leaving the network does not, by itself, automatically create a Marketplace Special Enrollment Period. Do not cancel existing coverage while investigating alternatives.
Marketplace and employer coverage
For Marketplace insurance, review the official Special Enrollment Period eligibility rules. Losing qualifying coverage, certain household changes and other eligible circumstances can create enrollment opportunities. A network change alone generally does not.
If your health plan comes through an employer, ask the benefits administrator whether any permitted midyear election change applies. Employer enrollment rules differ from Marketplace rules, and dissatisfaction with a network is generally not enough on its own.
During open enrollment, you can compare options for the next coverage period. Verify the enrollment deadline and effective date through the applicable Marketplace or employer before making a decision.
Medicare Advantage and Medicaid
Medicare Advantage members can generally change plans during the annual October 15 through December 7 enrollment period. People already enrolled in Medicare Advantage also have a January 1 through March 31 open enrollment period with specific switching rules.
Certain significant network changes may support a Medicare Special Enrollment Period, but not every doctor’s departure qualifies. Contact Medicare to ask about the specific situation. The official Medicare Plan Compare tool can help identify alternatives, but confirm provider participation directly before enrolling.
Medicaid managed-care members should contact their state program about continuity protections and whether changing managed-care plans is permitted. Enrollment and plan-change rules vary by state.
Compare your health plan options before switching
Keeping a trusted doctor matters, but a replacement policy should also cover the rest of your care. Confirm participation in the specific product and network for the new coverage year, rather than assuming another policy from the same insurer has the same doctors.
Compare the total expected cost: premiums, deductible, copayments and coinsurance. Check the in-network out-of-pocket maximum, but remember that premiums and many out-of-network charges do not count toward that limit.
Changing coverage can also mean starting a new deductible and out-of-pocket accumulation. Do not assume amounts already paid will transfer. Ask the new insurer about crediting rules before switching midyear.
Review prescription coverage by exact drug, dose and formulation. A medication may be covered but subject to prior authorization, step therapy or a different pharmacy requirement. Confirm specialist referrals, hospital access and any ongoing therapy or equipment needs as well.
If you regularly travel or receive care across state lines, ask specifically about routine out-of-area coverage. Emergency access does not establish coverage for planned follow-up visits elsewhere.
Use a written comparison rather than choosing solely on the premium or one physician’s participation. This health insurance renewal checklist can help organize the broader review once the immediate care issue is addressed.
Frequently asked questions
Can I keep seeing the doctor if I pay cash? The practice may allow self-pay visits, but ask about its policies and get a written estimate. If your health plan does not cover the visit, the payment generally will not count toward your in-network deductible or out-of-pocket maximum. Self-pay is not a substitute for checking continuity protections first.
Does an existing referral guarantee in-network coverage? No. A referral, prior authorization and network participation are separate issues. Confirm all three for the actual date of service, especially if an appointment moves beyond the doctor’s termination date.
What if I am pregnant or receiving cancer treatment? Request a continuity-of-care review promptly. Pregnancy treatment and treatment for qualifying serious and complex conditions are among the circumstances addressed by federal protections for applicable private plans. Approval, duration and documentation still depend on the relevant rules and your situation.
Can the insurer assign me a new primary care doctor? Some plans assign a replacement when a primary care provider leaves. Check the assignment, confirm the clinician accepts new patients and ask how to select a different participating doctor if needed. Also check whether specialist referrals must be updated.
Get help comparing the next step
First protect the care already underway. Confirm the termination date, submit any continuity request and obtain written cost information before deciding to leave your health plan.
If switching becomes appropriate, Insurance2All offers free, no-commitment quotes, comparisons from 50+ carriers and guidance from licensed advisors. Bilingual support and enrollment application assistance are also available. Bring the exact names of your doctors, medications and facilities so those needs can guide the comparison.