
The monthly premium shown in medicare quotes is only part of what you may pay. A quote can help you compare plans, but it usually is not a complete forecast of your medical bills, prescription spending or access to specific doctors.
Before choosing coverage, separate three things: the price to keep the coverage, the costs when you use it and the rules that determine whether a service is covered. A plan that looks inexpensive on the first screen may cost more once you account for those details.
What you can expect to see in a quote
There is no single standard format for a Medicare insurance quote. A short online result might display a premium and a few benefits. A more detailed comparison may include deductibles, copayments and estimated prescription costs based on information you entered.
What appears also depends on the coverage you are comparing. Medicare Advantage, standalone Part D and Medicare Supplement Insurance (Medigap) serve different purposes, so their prices are not interchangeable.
| Quote detail | What it usually tells you | What still needs checking |
|---|---|---|
| Monthly plan premium | The recurring charge for that particular policy | Other premiums you must pay separately |
| Deductible | An amount you may pay before certain benefits apply | Which services or drug tiers are subject to it |
| Copayments or coinsurance | Your share of selected covered services | Charges for other services and repeated visits |
| Out-of-pocket maximum | A spending limit for covered medical services under Medicare Advantage | What counts toward it and whether separate network limits apply |
| Extra benefits | Whether dental, vision, hearing or similar benefits are advertised | Allowances, frequency limits, networks and exclusions |
When comparing medicare quotes, first identify the type of policy behind each price. A Medigap premium buys supplemental coverage alongside Original Medicare; a Medicare Advantage premium applies to a private plan that provides your Part A and Part B benefits.
If that distinction is unclear, Insurance 2ALL’s explanation of how Medicare Advantage plans work provides useful background before you compare prices.
A quote is not the complete coverage contract
Treat a quote as a starting point, not a coverage guarantee. For Medicare Advantage and Part D, the Summary of Benefits provides a concise overview, while the Evidence of Coverage explains the plan’s benefits, costs and rules in greater detail.
The formulary lists covered drugs. The provider directory identifies participating clinicians and facilities, though participation should also be confirmed directly with the plan and provider. For Medigap, review the insurer’s policy materials and any conditions attached to the quoted rate.
A comparison tool’s estimated annual cost is also different from a guaranteed bill. It depends on assumptions about your prescriptions, pharmacies and healthcare use. If those inputs are incomplete, the estimate may not reflect your situation.
What medicare quotes leave out of the monthly price
Part B and other separately billed costs
A Medicare Advantage plan advertised with a $0 monthly premium does not mean all your Medicare coverage is free. You generally must continue paying your Part B premium, unless assistance or another arrangement covers it.
Some Advantage plans offer a Part B premium reduction, but that benefit is plan-specific and may cover only part of the premium. Check the amount and conditions rather than assuming Part B disappears from your budget.
Other costs that may sit outside a displayed plan premium include a Part A premium if you do not qualify for premium-free Part A, a separate Part D policy or a Medigap policy. Which ones apply depends on your coverage arrangement.
Higher-income beneficiaries may also owe an income-related monthly adjustment amount (IRMAA) for Part B and Part D. Late-enrollment penalties can add costs as well. These are not simply charges set by the private insurer. Medicare’s official explanation of Medicare costs helps distinguish them from plan premiums.
What you pay when you receive care
A specialist copayment tells you little about the cost of surgery, rehabilitation or a hospital stay. Depending on the plan, those services may involve different copayments, daily charges or coinsurance, which is a percentage of an allowed cost.
Useful medicare quotes show more than routine office visits. Look for the services you realistically expect to use, such as outpatient imaging, physical therapy, durable medical equipment or recurring specialist care.
Medicare Advantage plans have an annual out-of-pocket limit for covered Part A and Part B services. Premiums and Part D prescription costs do not count toward that medical limit. A PPO may also have different limits for in-network care and combined in-network and out-of-network care.
Original Medicare has no annual out-of-pocket limit for Part A and Part B services unless you have supplemental coverage that provides relevant protection. That is one reason a comparison based only on premiums can be misleading.
Your actual prescription spending
A Part D premium does not tell you what your medications will cost. Your spending depends on the exact drug, dosage, quantity, formulary tier and pharmacy, plus any deductible or coverage restrictions.
A covered drug may still require prior authorization, step therapy or a quantity limit. A preferred pharmacy may have different cost sharing from another pharmacy in the same network.
Before accepting an estimate, check that every current medication has been entered correctly. Include medications taken only occasionally if you expect to refill them during the coverage year.
Part D has a separate annual out-of-pocket cap for covered prescription drugs, and the amount changes by year. Premiums and spending on drugs the plan does not cover do not count toward that protection. The cap also does not apply to medications covered under Part B, which follow medical coverage rules instead.
Coverage details that a headline price cannot explain
Whether your doctors and services fit the plan
Two plans with similar premiums can provide very different access to care. With Medicare Advantage, check your primary care clinician, specialists, preferred hospital and any facility you use for ongoing treatment.
When reviewing medicare quotes, confirm the exact plan name and coverage year, not just whether a doctor accepts the insurance company generally. One carrier may offer several plans with different networks.
Also check referral and prior-authorization requirements. Being in-network does not automatically mean every proposed service is covered without additional approval.
Original Medicare works differently from Medicare Advantage networks. Ask whether a provider accepts Medicare and whether they accept assignment, which affects how approved charges are handled. With either coverage arrangement, avoid relying on a general statement such as “we take Medicare” when you need a more specific answer.
The limits behind dental, vision and hearing benefits
An advertised dental benefit might cover preventive services but place separate limits on crowns, dentures or other major work. A hearing benefit might apply only to selected devices purchased through designated providers.
Look for annual allowances, service frequency limits, cost sharing and participating-provider requirements. The benefit’s presence is less informative than what it would pay toward the service you need.
Quotes also cannot turn an excluded service into covered care. Medicare generally does not cover long-term custodial care, and Original Medicare generally excludes routine dental care and routine eye exams for glasses. Medicare Advantage may offer some additional benefits, but those benefits have their own terms. Check Medicare’s coverage information alongside the plan documents.
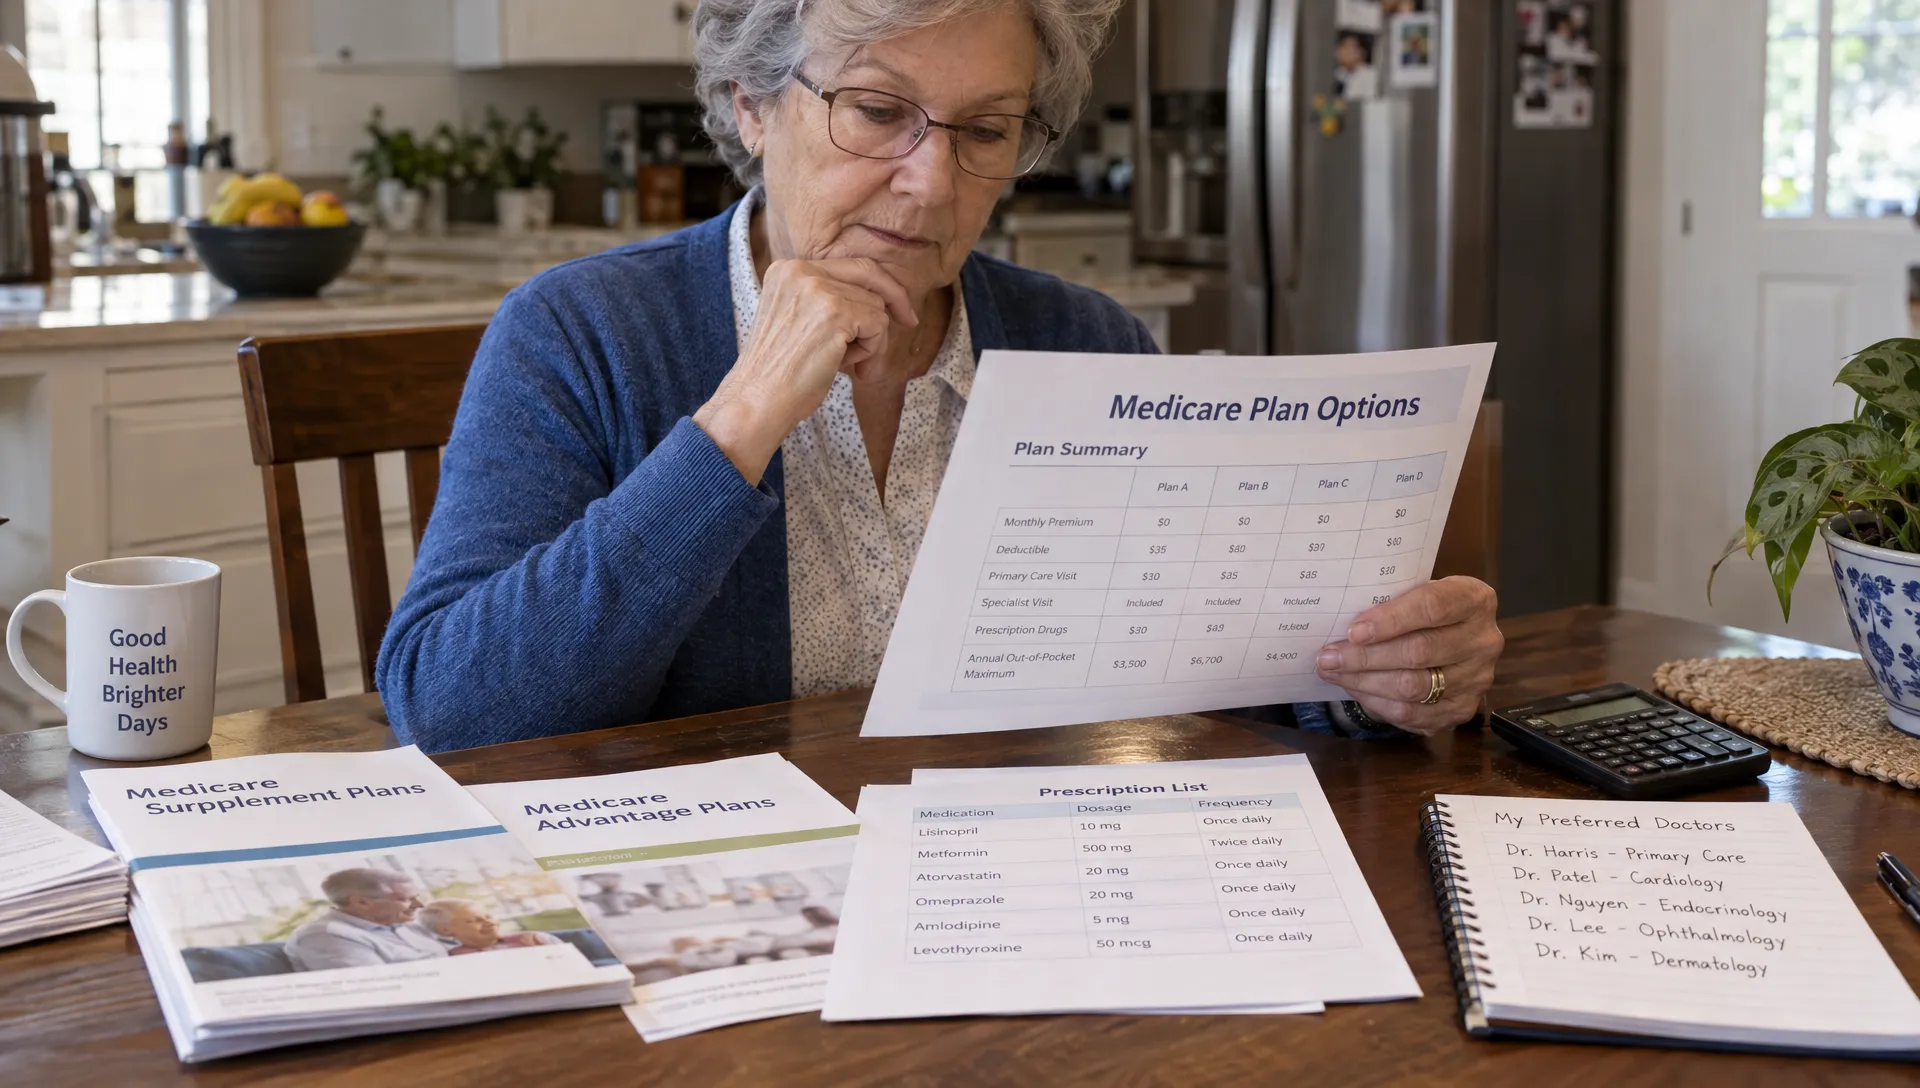
How to compare plans without overlooking the missing pieces
Use identical information for every comparison
Start with your ZIP code, intended coverage year, Medicare enrollment details, medication list and preferred pharmacies. Add your doctors, hospitals and any predictable treatments.
Location matters because plan availability and pricing can vary by service area. The year matters because premiums, benefits, formularies and networks can change annually. In the fall, make sure a result for the current year is not being compared with a result for the following year.
The most useful medicare quotes are based on the same inputs. Otherwise, a lower estimated cost may simply reflect a missing medication or a different pharmacy rather than better value.
You can use the official Medicare Plan Finder to compare available Medicare Advantage and Part D options. When working with an advisor, ask which carriers and plans are represented in your area.
Estimate both ordinary spending and a high-use year
Build an annual estimate rather than comparing monthly premiums alone:
Estimated annual spending = all applicable premiums for 12 months + expected medical cost sharing + expected prescription spending.
For Original Medicare with Medigap and Part D, include each applicable premium. For Medicare Advantage, include the plan premium, any separately payable Medicare premiums and expected cost sharing. Medigap is not used to pay Medicare Advantage copayments or deductibles.
Consider a hypothetical comparison: one plan has a $0 monthly plan premium and another charges $40. The second plan costs $480 more per year in plan premiums. If it would reduce your covered medical and prescription expenses by $600, it could cost $120 less overall, assuming other costs are equal. Those figures are illustrative, not actual plan prices.
Then examine a higher-use scenario involving hospitalization or substantial outpatient care. A medical out-of-pocket maximum helps assess risk under Medicare Advantage, but it is not an all-inclusive ceiling on premiums, prescriptions and uncovered services.
Check enrollment and pricing conditions before switching
A displayed price does not establish that you can enroll immediately. Medicare Advantage and Part D enrollment depends on eligibility, service area and an applicable enrollment period.
The annual fall enrollment period runs from October 15 through December 7, with changes generally effective January 1. Other enrollment opportunities have their own eligibility requirements.
Medigap follows different rules. Outside your Medigap Open Enrollment Period or applicable guaranteed issue rights, an insurer may use medical underwriting, subject to state rules. An initial rate may therefore require further review before it becomes an offer you can accept.
Before acting on medicare quotes, ask whether the price is final, what enrollment opportunity applies and what coverage would end when the new policy starts. Do not cancel existing supplemental coverage until you understand whether you can obtain the replacement. Medicare explains these considerations in its guidance on buying a Medigap policy.
Frequently asked questions
Does a $0-premium Medicare Advantage plan include the Part B premium? Usually not. You generally continue paying Part B separately. Some plans offer a premium reduction, and some beneficiaries qualify for assistance, but neither should be assumed from a $0 plan premium.
Are Medicare quotes a guarantee of my final costs? No. A quoted premium may be accurate for the stated circumstances, but your total spending depends on services used, prescriptions, coverage rules and other charges. Estimated annual costs are projections, not guarantees.
Can I compare a Medigap quote directly with a Medicare Advantage quote? Not by premium alone. Compare the complete coverage arrangements, including other premiums, prescription coverage, provider access and potential medical cost sharing. Medigap supplements Original Medicare rather than replacing it.
Will next year’s coverage match this year’s quote? Not necessarily. Annual plan changes can affect prices, benefits, drug coverage and provider networks. Use medicare quotes for the year you intend to enroll and review the corresponding plan documents before making a decision.
Review the complete cost before you enroll
A useful comparison should explain both the advertised price and the costs or restrictions outside it. Bring your medication list, preferred providers and questions about likely care to the conversation.
You can compare coverage with Insurance 2ALL through free, no-commitment quotes and guidance from licensed advisors. Bilingual support and enrollment application assistance are available. Ask the advisor to walk through separately billed premiums, prescription estimates and coverage rules before you choose a plan.