A low monthly premium does not tell you whether cheap health insurance plans will cover your prescriptions, preferred hospital or next unexpected illness. Some inexpensive policies provide comprehensive coverage with higher cost sharing. Others leave out major benefits or pay only a fixed amount toward a much larger bill.
The goal is to distinguish lower-cost coverage from less coverage. Before enrolling, check the policy type, calculate your financial exposure and test the benefits against care you actually use. The process below helps you identify gaps before they become unpaid claims.
Start by identifying what kind of policy you are buying
First, ask whether the product is ACA-compliant individual major medical insurance. Marketplace plans must cover essential health benefits, including hospitalization, prescription drugs, maternity care and mental health services. They also cannot exclude treatment because of a pre-existing condition. HealthCare.gov explains the benefits Marketplace plans must cover.
Short-term insurance, fixed-indemnity policies and health care sharing arrangements are different products. They do not necessarily provide those same protections. For example, a hospital indemnity policy may pay a set dollar amount per hospital day rather than cover your hospital bill.
An off-Marketplace plan is not automatically limited coverage. Insurers also sell ACA-compliant plans directly, so verify the policy rather than judging it by where it is advertised.
Which documents reveal gaps in cheap health insurance plans?
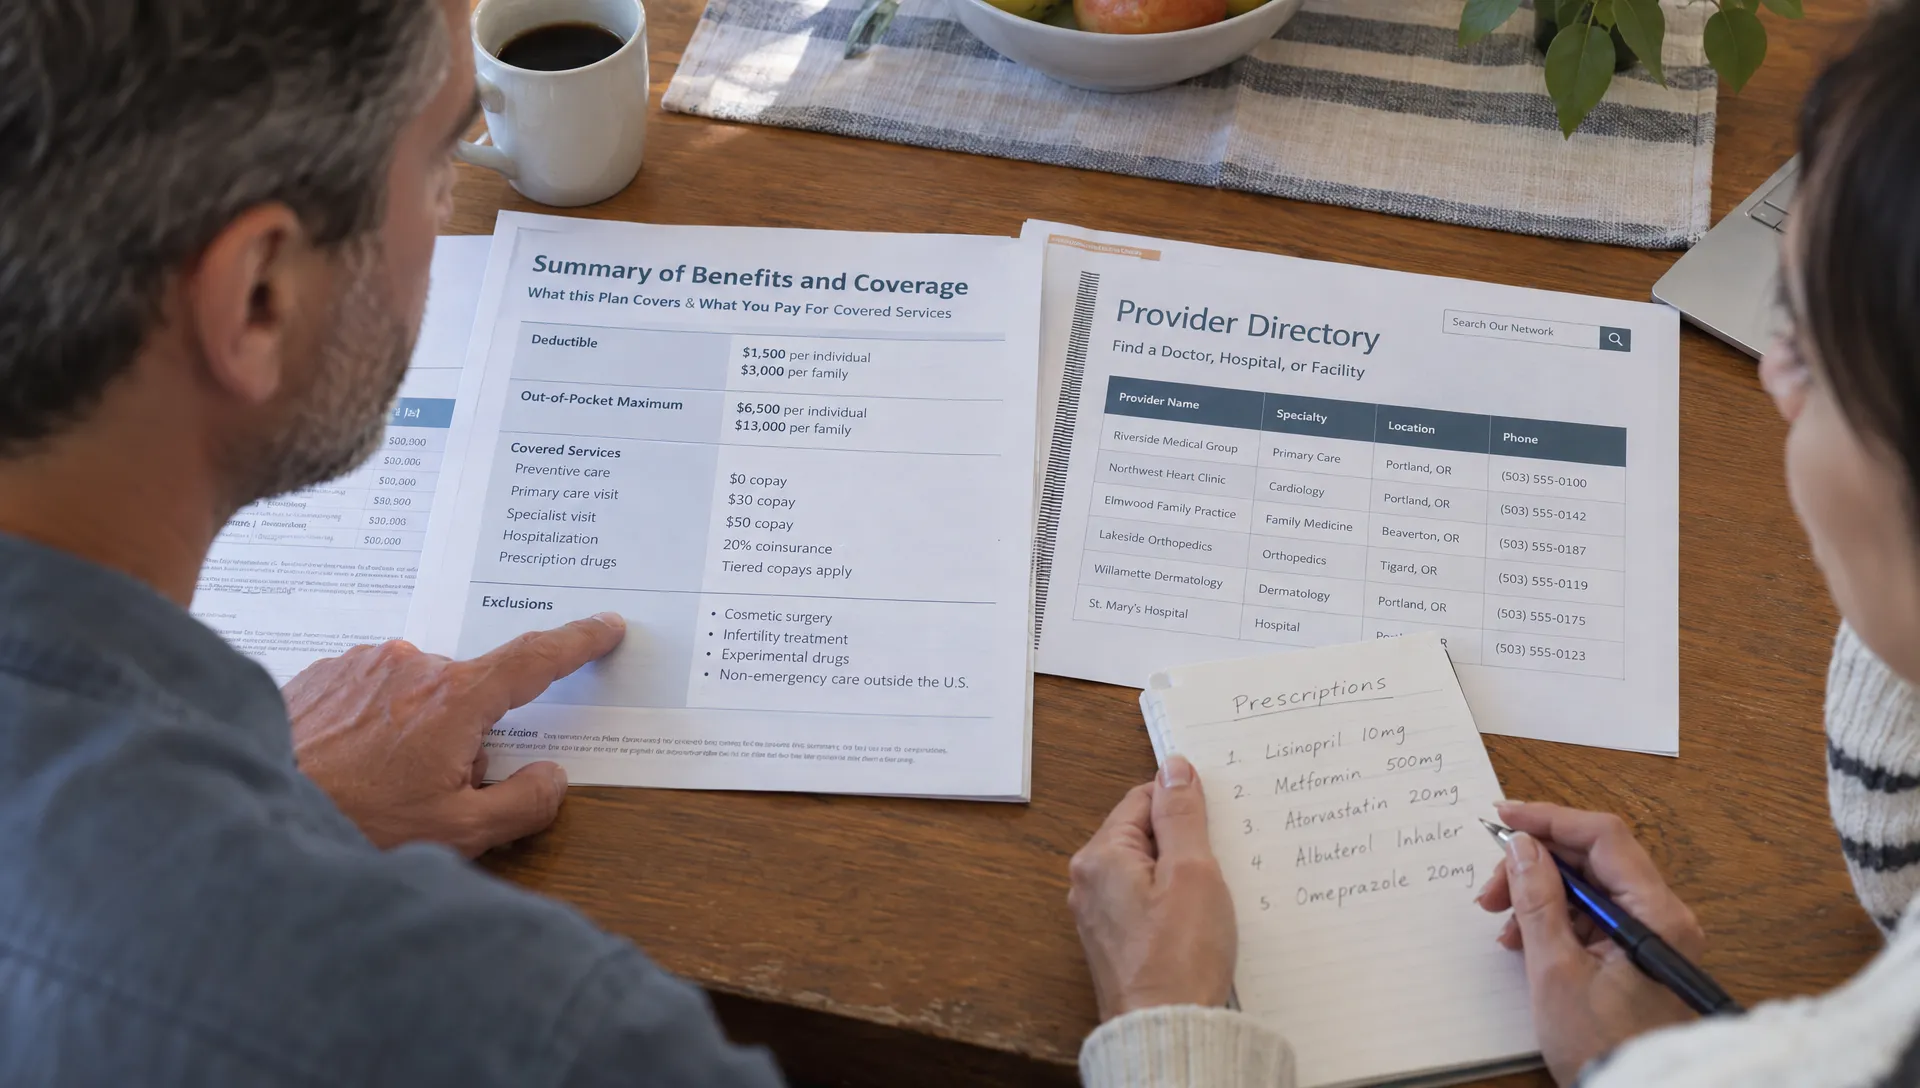
Request the Summary of Benefits and Coverage (SBC) for the exact plan and coverage year. This standardized document summarizes deductibles, cost sharing, exclusions and common treatment examples. The federal guide to the SBC explains its purpose.
Then check the detailed policy or Evidence of Coverage, provider directory and prescription drug formulary. The SBC is a starting point, not a complete contract. Its childbirth or diabetes examples are illustrations, not personalized price estimates.
Be cautious if a seller provides only a brochure, promises that “everything is covered” or avoids explaining exclusions in writing. If you are comparing temporary coverage, review the differences between ACA Marketplace and short-term health insurance before treating them as interchangeable.
Calculate your total exposure, not just the premium
Your premium keeps the policy active. Your deductible, copays and coinsurance determine what you pay when you receive care. Depending on the benefit, a copay may apply before you meet the deductible, while other services require you to pay the negotiated rate first.
When comparing cheap health insurance plans, calculate both a low-use year and a year with substantial covered medical expenses. These fictional plans illustrate why the cheapest monthly payment may not produce the lowest annual cost:
| Cost component | Example Plan A | Example Plan B |
|---|---|---|
| Monthly premium | $120 | $220 |
| Annual premiums | $1,440 | $2,640 |
| Individual deductible | $6,000 | $2,500 |
| In-network out-of-pocket maximum | $9,200 | $7,500 |
| Annual premiums plus out-of-pocket maximum | $10,640 | $10,140 |
These are examples, not quotes. If you need little care, Plan A could cost less. If covered in-network expenses take you to the out-of-pocket maximum, Plan B would cost $500 less overall under these assumptions.
Do not add the deductible to the out-of-pocket maximum again. Covered in-network deductible payments generally count toward that maximum, along with applicable copays and coinsurance.
Premiums, noncovered services and many out-of-network expenses do not count toward it. The figure is therefore not a ceiling on every dollar your household could spend. For family coverage, also check how individual and family deductibles and limits interact.
Check the network at the service level
One of the most consequential gaps in cheap health insurance plans is a network that does not match where you receive care. An insurer's name alone is not enough: the same company may operate several networks with different participating providers.
Search the directory using the exact plan name. Then confirm participation with both the insurer and the provider's billing office. Ask about the specific location and clinician, not just the medical practice. Save any written confirmation or call reference number.
For planned treatment, check the hospital or surgery center, surgeon, laboratory and imaging provider. An in-network doctor may refer you to a facility that is outside your network.
HMOs and EPOs generally restrict routine out-of-network coverage, while PPOs may cover some out-of-network care at a higher cost. The policy determines the details, including referral requirements.
Federal surprise-billing protections apply to many emergency services and certain services at in-network facilities, but they do not eliminate every out-of-network bill. Ground ambulance services are a notable gap in federal protections, although state protections may apply. For a medical emergency, seek care rather than delaying treatment to check a directory.
Look up each prescription, including its restrictions
A plan advertising “prescription coverage” may still be expensive for someone taking a particular medication. Compare the exact drug name, strength and formulation. A covered tablet does not necessarily mean the extended-release version is covered on the same terms.
To evaluate cheap health insurance plans accurately, check each medication's formulary tier, deductible treatment and pharmacy requirements. A preferred generic may have a modest copay, while a specialty medication may require percentage-based coinsurance.
Look for prior authorization, step therapy and quantity limits. These requirements can affect whether the insurer pays immediately, requires another treatment first or limits how much medication you can obtain at once.
Also verify whether your pharmacy is preferred, merely in-network or excluded. Some drugs must come from a designated specialty pharmacy.
If your medication is not listed, ask about the formulary exception process before enrolling. Do not assume approval. Likewise, do not assume manufacturer assistance will count toward your deductible or out-of-pocket limit, because the treatment of that assistance can vary by plan and applicable law.
Read exclusions and limits as carefully as covered benefits
Coverage gaps fall into three categories: a service is excluded, a covered service has conditions or the policy pays less than the bill.
Start with care you already expect to need. Therapy visits, rehabilitation, durable medical equipment, fertility treatment, adult dental care and adult vision benefits deserve specific attention. Benefits and restrictions vary, and routine adult dental and vision services are generally not required Marketplace benefits.
The biggest warning signs in cheap health insurance plans are often in phrases such as “fixed benefit,” “pre-existing condition exclusion,” “waiting period” or “maximum benefit per service.” Determine what each means for the product you are considering.
ACA-compliant plans cannot impose annual or lifetime dollar limits on essential health benefits, but benefit rules and medical-necessity requirements still matter. Limited-benefit products may work very differently.
For example, a policy that pays $1,000 for a qualifying hospital admission does not promise to pay the remaining hospital charges. A discount program may reduce a participating provider's price without paying insurance benefits at all. Ask directly whether the product is insurance and what financial responsibility remains yours.
Run a likely treatment through the policy
Choose one realistic scenario, such as ongoing diabetes care, a pregnancy or an orthopedic injury. Then trace the services involved instead of checking only the headline benefit.
For a possible knee procedure, your review might include:
- Initial care: Is the specialist in-network, and is a referral required?
- Testing: Where can you obtain an MRI, and does it need prior authorization?
- Treatment: Are the surgeon and facility covered, and how does outpatient surgery cost sharing work?
- Recovery: Are physical therapy visits covered, limited or subject to additional approval?
Ask the insurer how each service would be processed under the exact policy. Written benefit explanations are more useful than a general assurance that surgery is covered. Any estimate still depends on the services actually delivered and how the claim is processed.
This exercise can expose a plan that covers the operation but makes the surrounding care difficult to access. Repeat it for each family member with recurring treatment needs. If a required service is excluded, include its likely full cost in your comparison rather than assuming it will help satisfy the deductible.
Check whether financial assistance changes the better choice
Before accepting a high deductible to lower your premium, check whether your household qualifies for a different source of savings. The least expensive suitable option may be Medicaid, CHIP, employer coverage or a Marketplace plan with financial assistance.
Premium tax credits reduce eligible households' Marketplace premiums. Cost-sharing reductions are different: they lower deductibles, copays, coinsurance and out-of-pocket limits for eligible people who enroll in a qualifying Silver Marketplace plan.
That distinction matters when comparing cheap health insurance plans. A Bronze plan with a lower premium can be less attractive than a Silver plan with cost-sharing reductions, depending on eligibility and expected care.
Children may qualify for Medicaid or CHIP even when their parents do not. A family does not necessarily need everyone on the same policy, although coordinating separate plans requires checking networks and household costs carefully.
Insurance2All's guide to qualifying for ultra-low-cost health plans explains the main assistance pathways. Use the official application for a current eligibility determination rather than relying on an advertisement's lowest displayed price.
Find the official enrollment route for your state
Start with HealthCare.gov's state Marketplace directory. It directs residents to the federal Marketplace or their state's exchange. The application can also help identify potential Medicaid or CHIP eligibility, with final procedures depending on the state.
Use the correct coverage year and ZIP code. Networks, premiums, formularies and benefit designs can change at renewal, even if the plan name looks familiar.
Marketplace enrollment generally requires Open Enrollment or a qualifying Special Enrollment Period. Medicaid and CHIP applications are available year-round. State deadlines and effective-date rules can differ, so confirm when coverage actually begins before canceling an existing policy.
Keep subsidy estimates from becoming a budget gap
A quoted premium after financial assistance depends on application information, including projected annual household income. For someone who freelances, changes jobs or gains employer coverage, that information may change substantially during the year.
When budgeting for cheap health insurance plans, treat an income-based premium as an estimate that may need updating. Report relevant household and income changes promptly rather than waiting until tax time.
As HealthCare.gov explains in its guidance on why to report changes, updates can affect both savings and eligibility. Too little advance assistance can leave you paying more each month than necessary. Too much can create a repayment obligation under the rules for that coverage year.
People receiving advance premium tax credits generally reconcile them on their federal tax return using Form 1095-A and Form 8962. Keep Marketplace notices and consult a qualified tax professional about your circumstances.
This is not a medical-benefit exclusion, but it can create a financial gap just as disruptive as an unexpected deductible. Review your projected income when work or household circumstances change.
Frequently asked questions
Is $100 a month good for health insurance? It can be, but the premium alone cannot establish value. Check whether the price includes income-based assistance, whether the policy is comprehensive major medical coverage and what you would pay for covered care. A $100 premium with an unsuitable network may be a poor fit.
Do cheap health insurance plans cover pre-existing conditions? ACA-compliant individual major medical plans do. Short-term and other limited products may exclude pre-existing conditions or apply different eligibility rules. Confirm the product type and read its exclusions before purchasing.
Can a covered service still leave me with a large bill? Yes. A service may be covered but subject to the deductible, coinsurance, network restrictions or authorization requirements. Ask both whether it is covered and how your share of the cost is calculated.
Does a zero-dollar premium mean free medical care? No. It means the monthly premium is zero under the quoted terms, often after assistance. Deductibles and other cost sharing may still apply. Check what services are available before the deductible and what counts toward the out-of-pocket limit.
What should I save before enrolling? Keep the SBC, detailed policy documents, drug formulary, network confirmations and written answers about important benefits. Confirm the effective date and any required first premium payment. For a denial later, request the written reason and follow the plan's appeal instructions and deadlines.
Compare price and protection together
The right comparison starts with your doctors, prescriptions, expected treatments and ability to handle an unexpected bill. Use those details to eliminate unsuitable cheap health insurance plans before choosing among the remaining premiums.
Insurance2All offers free, no-commitment quote comparisons from 50+ carriers, with licensed advisor guidance, bilingual support and enrollment application assistance. Bring your medication list, preferred providers and coverage questions so you can compare available options on more than the advertised monthly price.