Choosing Medicare health plans before planned surgery means checking more than whether an operation is covered. Your surgeon, hospital, anesthesia team, prescriptions and recovery services can each affect access and cost. A low monthly premium will not help much if your preferred hospital is outside the network or rehabilitation requires approvals you have not arranged.
Start with the surgery date, then compare the full course of care, from preoperative testing through follow-up visits. The goal is coverage that works when you need it, not just a plan that looks inexpensive on paper.
Start with your surgery date and coverage effective date
Before comparing benefits, ask your surgeon’s office for the expected procedure date, facility and likely recovery setting. Find out whether the procedure is expected to be inpatient or outpatient. An overnight hospital stay does not necessarily mean you have been admitted as an inpatient.
Next, confirm when any new coverage would begin. A plan selected during fall enrollment generally will not cover an operation performed before its January 1 effective date. Your existing coverage governs care received before the new plan starts.
If you are becoming eligible for Medicare, confirm your Part A and Part B effective dates first. Medicare eligibility commonly begins at 65, although some people qualify earlier through disability or certain medical conditions. You generally need both Part A and Part B to join Medicare Advantage.
Do not postpone medically necessary care solely to coordinate an insurance change without discussing the risks with your clinician. Surgery itself does not create a special right to change plans whenever you choose.
Compare Medicare health plans for surgery and recovery
The main choice is between Original Medicare, potentially supplemented by Medigap and Part D, and Medicare Advantage. These arrangements handle provider access and financial risk differently.
| Coverage arrangement | How it can affect planned surgery | Main issue to verify |
|---|---|---|
| Original Medicare, Parts A and B | Part A generally covers inpatient hospital care. Part B generally covers surgeon services and outpatient surgery. | Whether providers accept Medicare, applicable cost-sharing and whether you have supplemental coverage |
| Original Medicare with Medigap | Medigap helps pay certain Original Medicare deductibles, coinsurance or copayments, depending on the policy. | Whether you can enroll in the policy and what it pays |
| Medicare Advantage, Part C | A private plan provides your Part A and Part B benefits, usually with its own network and cost-sharing. | Participating providers, referrals, prior authorization and the medical out-of-pocket limit |
| Part D prescription coverage | Helps cover eligible outpatient prescriptions, either through a standalone plan or usually within Medicare Advantage. | Your medications, pharmacy network and drug restrictions |
Medigap is not an alternative name for Medicare Advantage, and you cannot use it to pay Medicare Advantage cost-sharing. It also does not replace prescription drug coverage.
When comparing Medicare health plans, follow the actual procedure through each arrangement rather than choosing based on extra benefits unrelated to surgery. Medicare’s surgery coverage guidance explains why the setting matters and why you should request an estimate before treatment.
Verify the whole surgical team, not just your surgeon
Ask both the plan and the provider to confirm participation in the exact plan you are considering, including the plan year and location. A practice saying it “takes” an insurance company does not establish that it participates in every Medicare Advantage product that company sells.
Confirm the surgeon, hospital or ambulatory surgical center, anesthesia group and any assistant surgeon. Ask about other providers likely to bill separately, such as radiologists or pathologists. Your surgeon’s hospital privileges do not establish that the hospital is in your plan’s network.
With Original Medicare, ask whether each provider accepts Medicare and whether they accept assignment. Accepting assignment means agreeing to the Medicare-approved amount as full payment for covered services, although your deductible and coinsurance can still apply.
For Medicare Advantage, check whether you need a referral and whether any out-of-network benefits apply. A PPO may cover some out-of-network care at a higher cost, but that does not make every provider willing to treat you.
For Medicare health plans with networks, a directory listing is a starting point, not the final confirmation. Record the date, representative’s name and reference number when you call. If you expect to recover near relatives in another county or state, verify that location too.
Check coverage rules and prior authorization before enrolling
Ask the surgeon’s billing office for the planned procedure codes, often CPT or HCPCS codes, along with the expected site of care. The procedure name alone may not be specific enough for a useful coverage or cost discussion.
Then ask the insurer whether the operation, imaging, equipment or rehabilitation requires prior authorization. Requirements can differ by service and setting. Some services under Original Medicare also have authorization or other coverage requirements, so do not assume approval rules apply only to Medicare Advantage.
Prior authorization is not a guarantee that every related charge will be paid. Eligibility, the services actually performed, provider participation and other coverage conditions still matter.
When reviewing Medicare health plans, ask who will submit each authorization, what documentation is needed and how the office will track the decision. If coverage changes before surgery, do not assume an approval from the old plan automatically carries over. Ask the new plan about transition-of-care protections and any review it requires.
If a request is denied, obtain the written explanation and appeal instructions. For time-sensitive care, ask whether an expedited decision is appropriate under the applicable rules.
Estimate the full bill, not just the monthly premium
Request estimates from both the surgical office and the facility. Ask what is included and what may be billed separately. A facility estimate may exclude the surgeon, anesthesia, imaging, pathology or equipment used after discharge.
Build your comparison around preoperative visits and testing, the operation, the hospital stay, prescriptions, rehabilitation and follow-up appointments. Include your other expected healthcare needs for the year.
A useful calculation is:
Expected annual spending = annual premiums + estimated medical cost-sharing + estimated prescription costs + services you expect to pay for yourself.
For example, a hypothetical plan costing $40 more per month adds $480 in annual premiums. Whether that is worthwhile depends on its expected surgery costs, provider access and benefits, not the premium difference alone.
Comparing Medicare health plans this way makes a $0 plan premium easier to evaluate. A zero-premium Medicare Advantage plan can still have deductibles, copayments and coinsurance, and you generally still owe the Part B premium unless assistance pays it.
Understand the limits of each cost estimate
Original Medicare has no annual out-of-pocket maximum for Part A and Part B services. Medigap may reduce that exposure, depending on the policy. Without supplemental coverage, a percentage-based share of covered services can be substantial.
Medicare Advantage plans have an annual limit on your share of covered Part A and Part B services. Review the in-network limit and, where applicable, the combined in-network and out-of-network limit. Premiums and Part D drug spending do not count toward that medical limit.
Also distinguish calendar-year costs from benefit-period costs. Original Medicare’s Part A inpatient deductible applies by benefit period, not simply once each calendar year. Other deductibles and limits can reset when a new year begins. Ask how a December operation followed by January rehabilitation would be handled.
Include rehabilitation, equipment and take-home medications
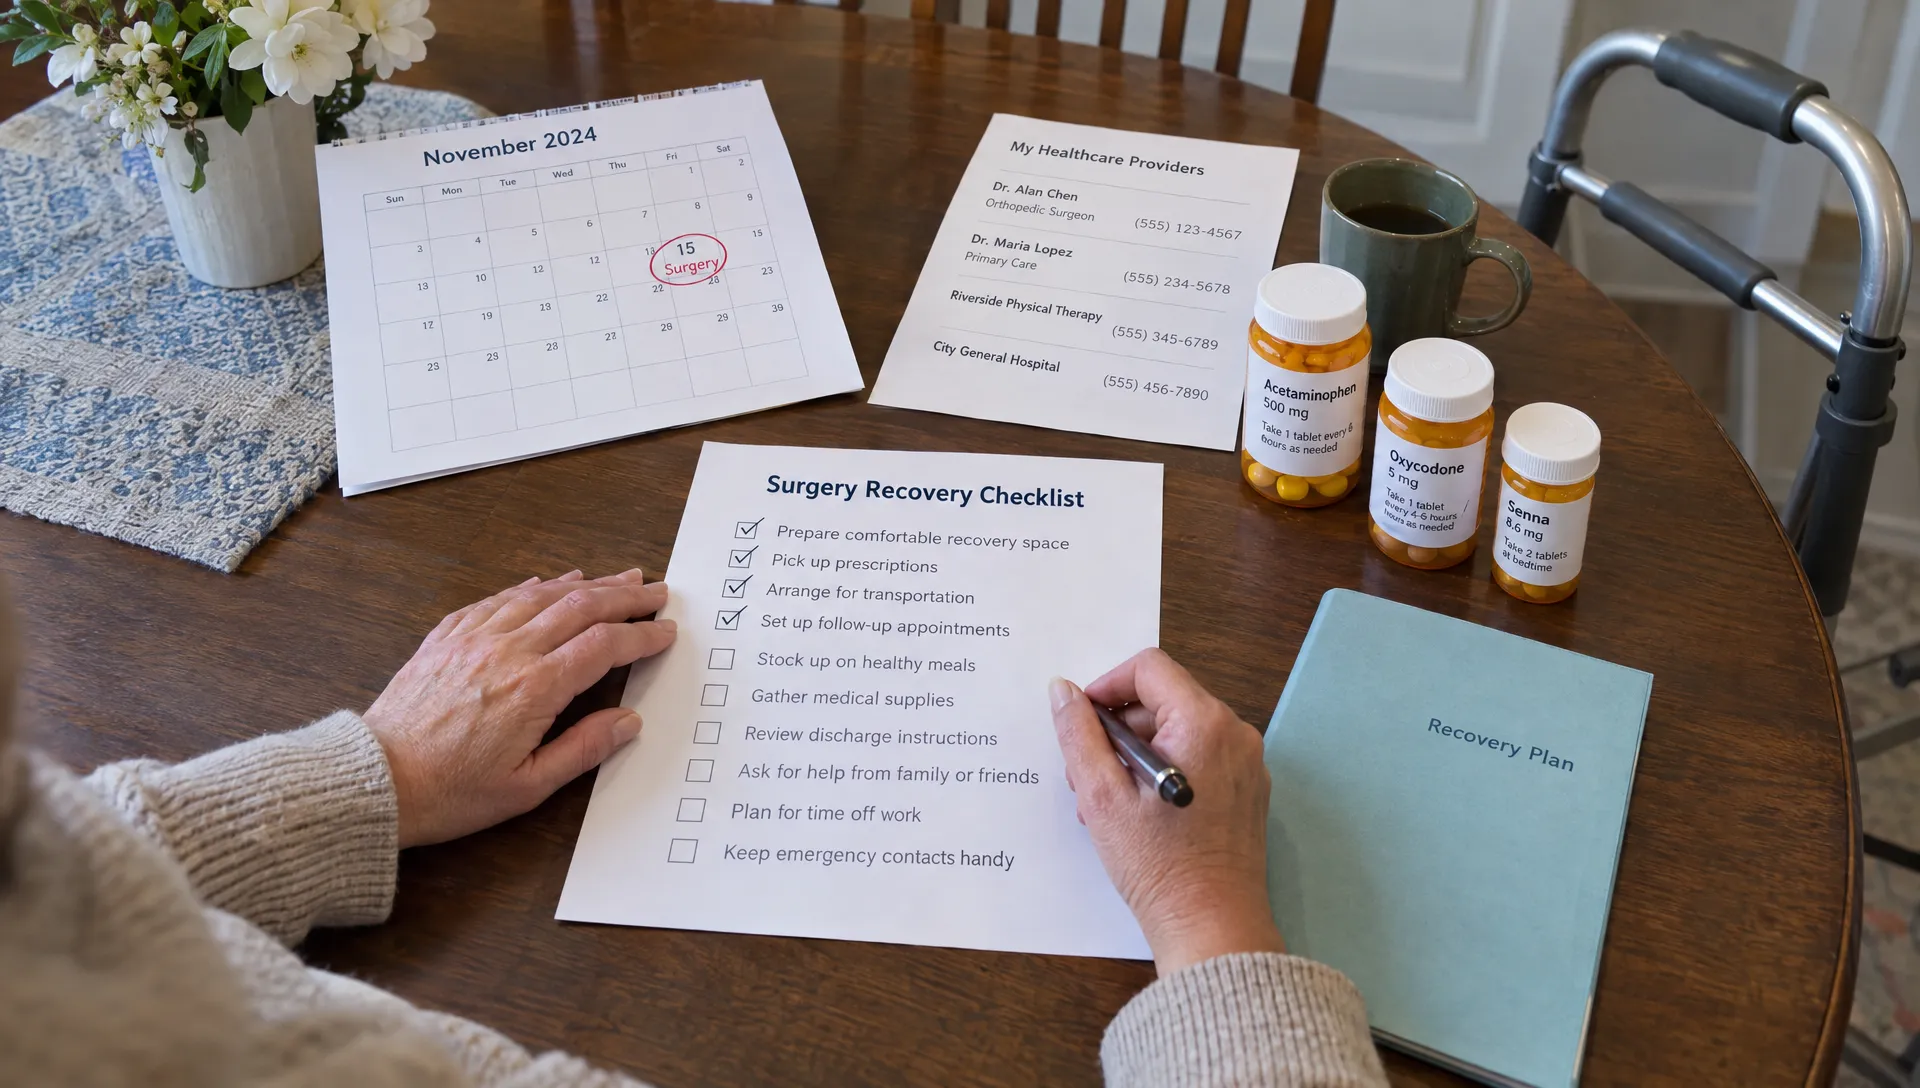
Discharge planning deserves as much attention as the operation. Ask whether you are likely to need outpatient physical therapy, home health services, a walker or a skilled nursing facility. Then verify the coverage requirements, available providers and expected cost-sharing for each.
Under Original Medicare, skilled nursing facility coverage generally requires a qualifying inpatient hospital stay of at least three consecutive days, excluding the discharge day, along with other conditions. Observation and emergency department time do not count toward that requirement. Certain waivers or arrangements can apply, and Medicare Advantage rules may differ. Medicare’s skilled nursing facility coverage requirements explain the conditions.
Medicare health plans should also be compared against the medications you may need at home. Ask the surgical team about likely prescriptions, then check the plan’s formulary, pharmacy network and any approval or quantity limits. Drugs administered during treatment may fall under a different benefit than prescriptions filled after discharge.
Medicare does not automatically cover every rehabilitation stay, and it generally does not cover long-term custodial care when that is the only care needed.
Match enrollment timing to the operation
If you are comparing coverage in November 2026, Medicare’s annual Open Enrollment Period runs from October 15 through December 7. Changes made during this period generally take effect January 1, 2027. Review the coming year’s documents, not just the benefits currently in effect.
For a December operation, a January plan change will not replace the coverage governing the December surgery. It can, however, affect January therapy, prescriptions and other follow-up services. Confirm how both plans would handle the episode of care, including any visits bundled into surgical payment.
The Medicare Advantage Open Enrollment Period runs from January 1 through March 31 for people already enrolled in Medicare Advantage. It generally permits one change to another Medicare Advantage plan or a return to Original Medicare, with the opportunity to join a standalone drug plan. It is not a general enrollment window for everyone.
Before switching Medicare health plans, confirm your enrollment eligibility and effective date. Initial enrollment and qualifying Special Enrollment Periods follow different rules. Insurance2All’s guide to getting help with Medicare enrollment explains the different sources of assistance.
Check Medigap eligibility before leaving Medicare Advantage
Returning to Original Medicare does not automatically guarantee that you can buy the Medigap policy you want.
Your federal Medigap Open Enrollment Period generally lasts six months, starting the first month you are 65 or older and enrolled in Part B. Outside that period, an insurer may use medical underwriting unless you have a guaranteed issue right or another applicable protection. State rules can provide additional rights, including protections for some people under 65.
A planned operation makes this especially important. Do not cancel existing coverage on the assumption that a supplement will be available. Confirm eligibility, acceptance, premium and effective date first. Medicare explains these protections in its guidance on when to buy Medigap.
Get these answers before submitting an application
Bring your procedure information, provider names and medication list to each comparison. Ask the plan and surgical office to resolve any conflicting answers rather than relying on a sales summary.
- Access: Are the surgeon, facility and likely recovery providers covered under this exact plan?
- Approval: Which services need referrals or authorization, and who will obtain them?
- Costs: What are the estimated separate charges, applicable deductibles and medical out-of-pocket limits?
- Recovery: Are the expected therapy, equipment, prescriptions and discharge setting covered?
- Timing: Will coverage be active for each stage of care, and what changes after January 1?
For Medicare health plans on your shortlist, review the Summary of Benefits and relevant Evidence of Coverage sections. Keep estimates, authorization decisions and enrollment confirmations together.
You can use Medicare Plan Compare to review available plans by ZIP code. If you have Medicaid, employer coverage or retiree benefits, check how a change would affect that coverage before enrolling. Your State Health Insurance Assistance Program, or SHIP, can provide free, impartial Medicare counseling.
Frequently asked questions
Will Medicare cover my planned surgery? Medicare generally covers medically necessary surgery when applicable coverage requirements are met. Coverage depends on the procedure, setting and other conditions. Cosmetic procedures are generally excluded unless a specific exception applies. Confirm your procedure with Medicare or your plan rather than relying on the operation’s name alone.
Is Original Medicare or Medicare Advantage better before surgery? Neither is universally better. Original Medicare generally offers broad access to providers who accept Medicare but has no annual Part A and Part B spending cap. Medicare Advantage adds a medical out-of-pocket limit but can involve networks and prior authorization. Compare Medicare health plans against your actual surgical team and recovery needs.
Can I change plans because surgery has been scheduled? Scheduling an operation does not, by itself, create a Special Enrollment Period. You need an applicable enrollment window or another qualifying circumstance. Confirm the effective date before assuming a new plan will pay.
Does staying overnight satisfy Medicare’s inpatient requirement? Not necessarily. You can stay overnight under outpatient observation status. Ask the hospital about your formal status, especially if you may need skilled nursing facility care after discharge.
Get help comparing coverage around your surgery
Bring your surgery date, provider list, prescriptions and recovery expectations to an Insurance2All licensed advisor. Insurance2All offers free, no-commitment Medicare plan comparisons, bilingual guidance and enrollment application support.
Request Medicare plan comparison help from Insurance2All to review available options. Before enrolling, confirm the provider network, authorization requirements and effective date for the exact plan you choose.