Your health plan may work perfectly near home but offer much less coverage when you visit family, take a work assignment or spend part of the year in another state. If you’re searching for health insurance national coverage, the key question is whether your specific plan covers the care you need where you’ll actually receive it. A familiar insurance company’s name does not guarantee nationwide access to doctors and hospitals.
The short answer: Some plans provide broad access across states. Others mainly cover local providers, with exceptions for emergencies and certain other services. Your network, plan documents and reason for receiving care determine the answer.
What health insurance national coverage actually means
“National coverage” can describe two different things: a nationwide health insurance system or an individual plan that provides access to care across the country. These meanings are not interchangeable.
The United States does not have one universal national health insurance program covering every resident. Instead, people receive coverage through employers, individual insurance, Medicare, Medicaid and other programs.
For someone comparing plans, the practical issue is geographic access. A plan can cover a broad range of medical services while offering a narrow provider network in one region. Conversely, a plan with a nationwide network may still exclude particular treatments or require prior authorization.
Covered benefits and nationwide provider access are separate features. You need to check both before relying on a plan away from home.
Which private plans work across state lines?
When comparing health insurance national coverage, start with the exact network attached to the policy, not just its HMO, PPO or EPO label. Those labels describe general plan structures, not a guarantee of nationwide access.
HealthCare.gov’s explanation of plan and network types outlines these common differences:
| Plan type | Typical rules for nonemergency care | What to check before traveling |
|---|---|---|
| HMO | Usually requires network providers, with limited exceptions | Whether the plan has an away-from-home arrangement |
| EPO | Generally covers care only within its network, except emergencies | Whether destination providers belong to your exact network |
| PPO | Usually permits out-of-network care at a higher cost | Whether it has a national network and separate out-of-network costs |
| POS | Often combines network requirements, referrals and some out-of-network coverage | Referral rules and benefits outside the local area |
An employer PPO may provide access to a broad national network. Another PPO may have a smaller network, leaving you with expensive out-of-network options elsewhere.
Individual Marketplace plans also vary by location and insurer. A carrier selling plans in several states does not necessarily let members use every provider it contracts with nationwide. Ask about your specific plan name and network, including any network available to traveling members.
Emergency coverage is not the same as routine coverage
Emergency protections are an important part of health insurance national coverage, but they do not make every out-of-state appointment covered.
For most private comprehensive health plans, the federal No Surprises Act limits out-of-network cost sharing and generally prohibits balance billing for covered emergency services. This can protect you when an emergency sends you to a hospital outside your network. CMS explains these protections through its medical billing rights guidance.
If you believe you are having a medical emergency, seek care immediately rather than delaying treatment to research networks.
Routine and follow-up care work differently. Consider a hypothetical trip during which you receive emergency treatment for a broken ankle. The emergency visit may receive federal billing protections, but a separately scheduled orthopedic appointment after discharge could be subject to your plan’s normal network and authorization rules.
An urgent care visit is not automatically an emergency for insurance purposes, either. A walk-in clinic may be out of network even if it advertises immediate appointments.
Ground ambulance bills are another important exception: federal No Surprises Act protections generally do not cover them, although state protections may apply. Ask about ambulance benefits before traveling, especially if you will be far from your usual hospitals.
How Medicare and Medicaid handle out-of-state care
Public programs follow different rules, so health insurance national coverage depends heavily on which program and coverage arrangement you have.
Original Medicare
With Original Medicare, you can generally use any doctor or hospital in the United States that accepts Medicare. This can make it useful for retirees who travel frequently or divide their time between states.
That does not mean every service is covered or free. Medicare’s coverage requirements and cost-sharing rules still apply. Prescription coverage through Part D has its own pharmacy network and formulary.
Medigap can help pay certain Original Medicare costs, but it does not turn an excluded service into a covered benefit. Medicare SELECT policies can also have network conditions for full supplemental benefits.
Medicare Advantage
Medicare Advantage plans must cover emergency and urgently needed care, including when you are away from the service area. Routine out-of-area care depends on the plan’s network and rules.
Some plans offer travel arrangements or out-of-network benefits, but you should not assume they do. Medicare’s comparison of Original Medicare and Medicare Advantage explains the main access differences.
Medicaid
Medicaid generally operates through the state where you qualify. Out-of-state coverage may be available for emergencies and certain other circumstances, but routine nationwide access is not a standard feature.
Contact your state Medicaid agency or managed care plan before arranging nonemergency treatment elsewhere. Provider enrollment and authorization requirements can affect whether the program pays.
Which services remain covered when you travel?
Evaluating health insurance national coverage means checking individual services, not just finding a nearby hospital. A covered service can still require an eligible provider, a referral or advance approval.
ACA-compliant individual and small-group plans cover essential health benefit categories, including hospitalization, prescription drugs and mental health services. However, that requirement does not make every provider nationwide in network. Large employer and self-funded plans operate under different benefit requirements.
For ongoing treatment, verify access to the entire care team. A cancer center might be in network while an affiliated specialist, laboratory or infusion provider is not.
Prescriptions deserve a separate check. Confirm that your medication is on the formulary, that a destination pharmacy participates and that refill timing will cover your trip. Specialty drugs may require a designated pharmacy or delivery arrangements.
If you also need help distinguishing covered services from exclusions, our guide to understanding your health coverage explains the underlying plan terms.
How to verify a plan before enrolling or traveling
The most useful test of health insurance national coverage is a specific scenario: “Can I receive this treatment, from this provider, in this location, under this exact plan?”
Review the documents that control coverage
Start with the Summary of Benefits and Coverage, then review the Evidence of Coverage, insurance certificate or employer plan document for more detail. Look for provisions about service areas, out-of-network care, referrals, prior authorization and travel.
The summary is a starting point, not a complete list of every condition or exclusion. An online provider directory alone is not enough to establish coverage.
Confirm providers with both sides
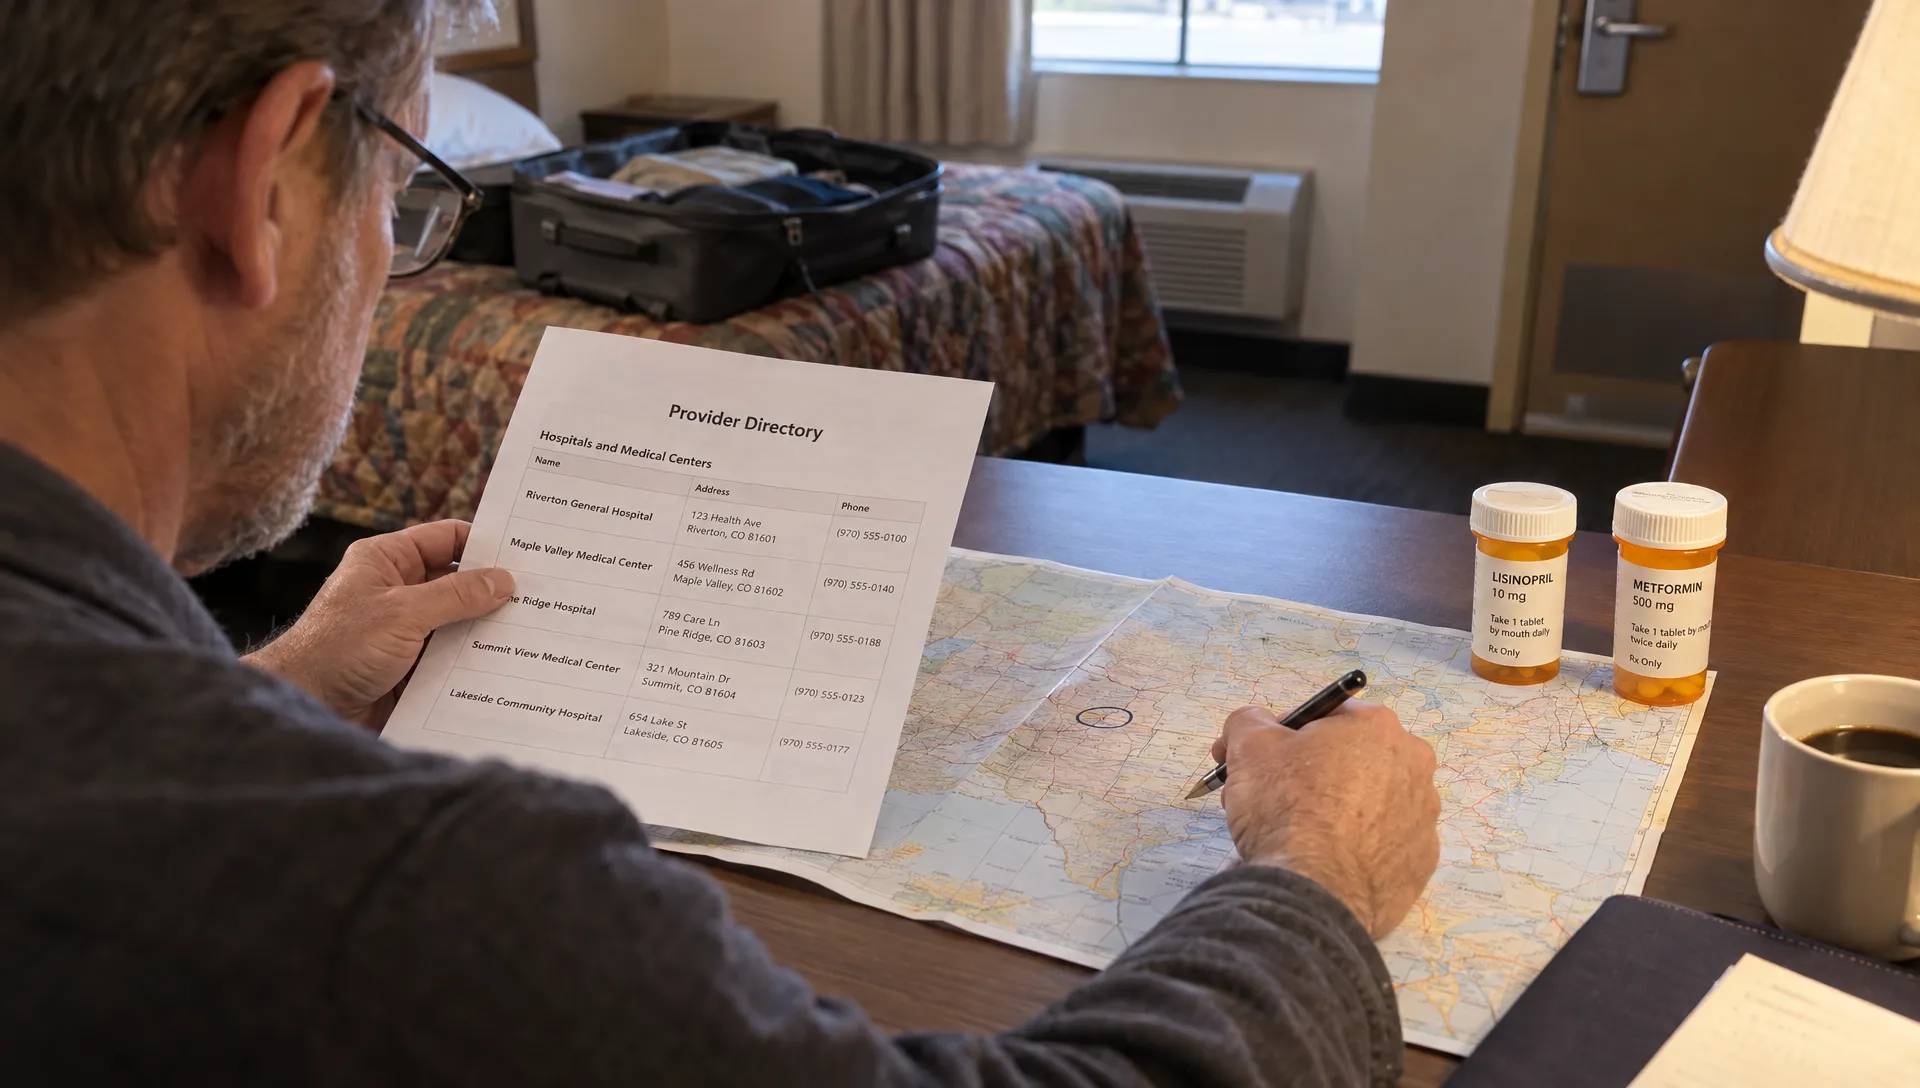
Give the insurer the provider’s name, practice address and, if available, National Provider Identifier. Ask whether that provider participates in your exact network at that location. Then ask the provider’s billing office to verify the same information.
For a planned procedure, confirm the facility and separately billing clinicians. When possible, request written confirmation through the insurer’s secure messaging system and retain call reference numbers.
Ask about the treatment, not only the doctor
Confirm whether the service needs prior authorization and whether an existing approval remains valid at a different facility. Ask about referral requirements, visit limits and any special rules for recurring care.
For telehealth, confirm both plan coverage and whether the clinician can legally treat you while you are physically in the destination state. An established relationship with a doctor does not automatically resolve interstate licensing requirements.
Compare total costs, not just the monthly premium
A plan offering health insurance national coverage can still expose you to substantial costs if its nationwide access relies mainly on out-of-network benefits.
Ask whether the destination provider is truly in network or merely eligible for out-of-network reimbursement. The financial difference can be significant.
| Cost item | Why it matters away from home |
|---|---|
| Deductible | A separate out-of-network deductible may apply |
| Coinsurance | Your percentage share may be higher outside the network |
| Allowed amount | The plan may calculate payment using less than the provider’s charge |
| Balance billing | Outside protected situations, a provider may bill amounts the plan does not pay |
| Out-of-pocket maximum | Noncovered care and many out-of-network charges may not count toward the limit |
For example, an out-of-network specialist might charge more than the insurer’s allowed amount. Unless a legal protection applies, you could owe both your normal cost sharing and the difference between those amounts.
Original Medicare also has no annual out-of-pocket maximum for Part A and Part B services. Supplemental coverage may reduce your share, but it is important to compare the full arrangement rather than premiums alone.
Traveling and moving require different checks
For health insurance national coverage to meet your needs, the plan must fit both your travel habits and its eligibility rules. Temporary travel is different from establishing a new permanent residence.
A vacation does not usually require changing your home address for enrollment purposes. A permanent move can change your available plans, service area and eligibility.
If you move to another state with Marketplace coverage, you generally need to apply through the Marketplace serving the new state and enroll in a new plan. A qualifying move may create a Special Enrollment Period, but conditions apply. HealthCare.gov explains how to update Marketplace coverage when you move.
Medicare Advantage and Part D members should report permanent moves because service-area changes can affect enrollment options. Medicaid members generally need to establish eligibility in the new state rather than assume their existing coverage transfers.
For employer coverage, ask human resources whether the move changes plan eligibility or network access. Before canceling an old policy, confirm the replacement policy’s effective date. Our explanation of when new health coverage begins can help you identify potential gaps.
Federal protections and state rules both matter
State insurance requirements do not apply identically to every plan. This distinction matters when checking health insurance national coverage, especially through an employer.
Many private-sector employers use self-funded plans, meaning the employer bears the financial risk even when an insurance company administers claims. These plans are generally governed by federal ERISA requirements rather than state insurance benefit mandates. Other applicable federal protections still matter.
Fully insured plans are subject to applicable state insurance regulation as well as federal law. Certain state surprise-billing or benefit requirements may therefore apply differently depending on how a plan is funded.
Ask your benefits administrator whether your plan is fully insured or self-funded. The logo on the insurance card does not answer that question. If a claim is denied, request the written reason and the plan provision supporting the decision, then review the available appeal process.
Frequently asked questions
Does a national insurance company cover me in every state? Not necessarily. A company may operate nationwide while your particular policy uses a local or regional network. Check the plan’s exact network, travel provisions and out-of-network benefits.
Can I keep using my doctor after moving to another state? Possibly, but it depends on your continued eligibility, the doctor’s network participation and the service involved. Telehealth also depends on where you are physically located and the clinician’s authority to practice there.
Does national coverage include international travel? No. Domestic nationwide access does not establish overseas benefits. Review international emergency coverage, exclusions and medical evacuation provisions separately. Original Medicare generally does not cover care outside the United States, with limited exceptions.
What is the best plan for someone living in two states? The best health insurance national coverage arrangement is one that includes your actual providers in both locations at manageable costs. Compare exact networks, residency requirements, prescription access and ongoing treatment needs rather than choosing solely by plan type.
Compare coverage that fits where you receive care
Before enrolling, write down the states you regularly visit, your preferred providers and any ongoing prescriptions or treatments. Use that list to compare specific policies.
Insurance2All offers free, no-commitment quote comparisons from 50+ carriers, with licensed advisor guidance, bilingual support and enrollment application assistance. Ask an advisor to help compare network access and plan terms for the places where you need care.