Medicare and life insurance protect against different financial problems, so some retirees need both. Medicare helps pay for covered healthcare while you are alive. Life insurance generally pays a death benefit to your beneficiaries after you die. One does not replace the other.
The deciding question is not simply whether you have reached retirement age. It is whether your death would leave someone with an income shortfall, debt or expenses they could not comfortably cover. If your savings already cover those needs, keeping or buying life insurance may be unnecessary. If someone still depends on you financially, coverage may remain useful.
What each type of coverage actually does
Medicare is individual health insurance, generally for people age 65 and older and certain younger people with qualifying disabilities or conditions. Life insurance is a separate contract designed to provide money after an insured person's death, subject to the policy's terms.
| Coverage | Main purpose | What it does not replace |
|---|---|---|
| Original Medicare, Parts A and B | Helps pay for covered hospital and medical services | A life insurance death benefit |
| Medicare Advantage, Part C | Provides Medicare-covered benefits through a private plan, usually including drug coverage | Financial support for survivors |
| Part D | Helps cover prescription drugs | Life insurance or comprehensive medical coverage |
| Medigap | Helps pay certain Original Medicare out-of-pocket costs | Life insurance, prescription drug coverage or most long-term custodial care |
| Life insurance | Pays beneficiaries under the policy's terms | Medicare or other comprehensive health insurance |
Comparing Medicare and life insurance starts with separating medical bills from survivors' financial needs. Medicare's hospice benefit covers qualifying end-of-life care, but it does not provide a life insurance payout or pay funeral and burial expenses.
When keeping both makes sense in retirement
Life insurance is most useful when your death would create a financial gap. A spouse, partner, adult child with disabilities or another dependent may still rely on your income or unpaid caregiving.
For married retirees, review income after the first death rather than assuming the household can continue on its current budget. A household receiving two Social Security retirement payments generally does not keep both after one spouse dies. Survivor benefit rules determine what continues. Pension income may also fall, depending on the survivor option selected.
Housing costs rarely fall in proportion to lost income. Property taxes, insurance and maintenance may remain similar even when only one person lives in the home. Life insurance can provide money to cover that mismatch or pay down a mortgage.
Keeping Medicare and life insurance can also make sense if you have a specific legacy goal, such as providing an inheritance without requiring your family to sell property. That is different from needing insurance for basic financial security, so weigh it against the ongoing premium.
You may not need life coverage if nobody depends on you, your debts are manageable and accessible savings already cover final expenses and your intended legacy. Retirement alone is neither a reason to cancel a policy nor a reason to buy one.
Calculate the survivor's financial gap first
Avoid choosing a death benefit solely from an age-based rule or a multiple of your former salary. In retirement, the more useful calculation is:
Estimated need = survivor income shortfall + debts to be paid + final expenses + other obligations, minus assets and existing coverage available for those purposes.
Consider this illustrative example, not a coverage recommendation. A retiree estimates that their spouse would need an additional $1,800 per month for five years after accounting for survivor benefits and other continuing income. That creates a $108,000 income gap. Add an assumed $40,000 debt payoff and $15,000 for final expenses, bringing the total to $163,000.
If $60,000 of accessible savings and an existing $25,000 death benefit are available for those needs, the remaining gap is $78,000. The five-year period and every dollar amount are assumptions to replace with your own figures.
When budgeting for Medicare and life insurance, keep healthcare reserves separate from money earmarked for survivors. Counting the same savings for both purposes can make your household appear better protected than it is.
Do not count home equity unless the survivor realistically intends and is able to access it. Similarly, retirement account balances may involve taxes or withdrawal constraints, so their full account value may not equal spendable cash.
Match the policy to the length of the need
Term coverage for a temporary obligation
Term life insurance provides coverage for a specified period. It can fit a need that has an expected end date, such as a mortgage payoff or a spouse's transition to another income source. Buying a new policy later in life may involve higher premiums or medical underwriting, and availability varies by insurer.
When a 30-year term ends, coverage generally expires unless the contract provides renewal, conversion or another continuation option. Standard term insurance does not refund premiums simply because you outlive the term. Renewal premiums can be substantially higher.
A retirement review of Medicare and life insurance should therefore include the expiration date of any existing term policy, not just its current premium.
Permanent coverage for an ongoing objective
Permanent life insurance is designed to remain in force for life if its funding and other policy requirements are met. Some policies build cash value. Review guarantees, nonguaranteed projections, loans and required premiums before relying on that coverage.
A smaller final-expense policy may address a limited need, but examine the cost relative to the death benefit. Some policies have graded benefits or waiting periods for certain deaths.
If you are leaving a job, verify what happens to employer-provided coverage. Insurance2All's comparison of employer and individual life insurance explains why portability and ownership deserve attention before retirement.
How Medicare and life insurance eligibility differ
Owning life insurance generally does not affect your eligibility for Medicare. Medicare eligibility is not based on an asset test, so a policy's death benefit or cash value does not ordinarily prevent enrollment.
Medicaid is different. Eligibility rules for some Medicaid categories, especially those involving long-term care, consider income and resources. Depending on the state, program and policy details, cash value may count as a resource. Exclusions may apply, but there is no single rule that fits every policyholder.
Assistance with Medicare costs has its own requirements. The official Medicare Savings Programs guidance explains that these state-administered programs have income and resource rules, with state-specific differences.
Premiums are another separate issue. Simply owning a policy does not trigger an income-related Medicare surcharge. However, taxable income from a surrender or another policy transaction can potentially affect income-related Part B and Part D premiums in a later year.
Before surrendering, transferring or changing ownership of a policy to qualify for assistance, get program-specific advice. Medicaid transfer rules can create consequences that a general insurance comparison cannot resolve.
Check ownership and beneficiaries, not just the payout
A policy has several distinct roles: the owner controls it, the insured is the person whose life is covered and the beneficiary receives the death benefit. These can be different people.
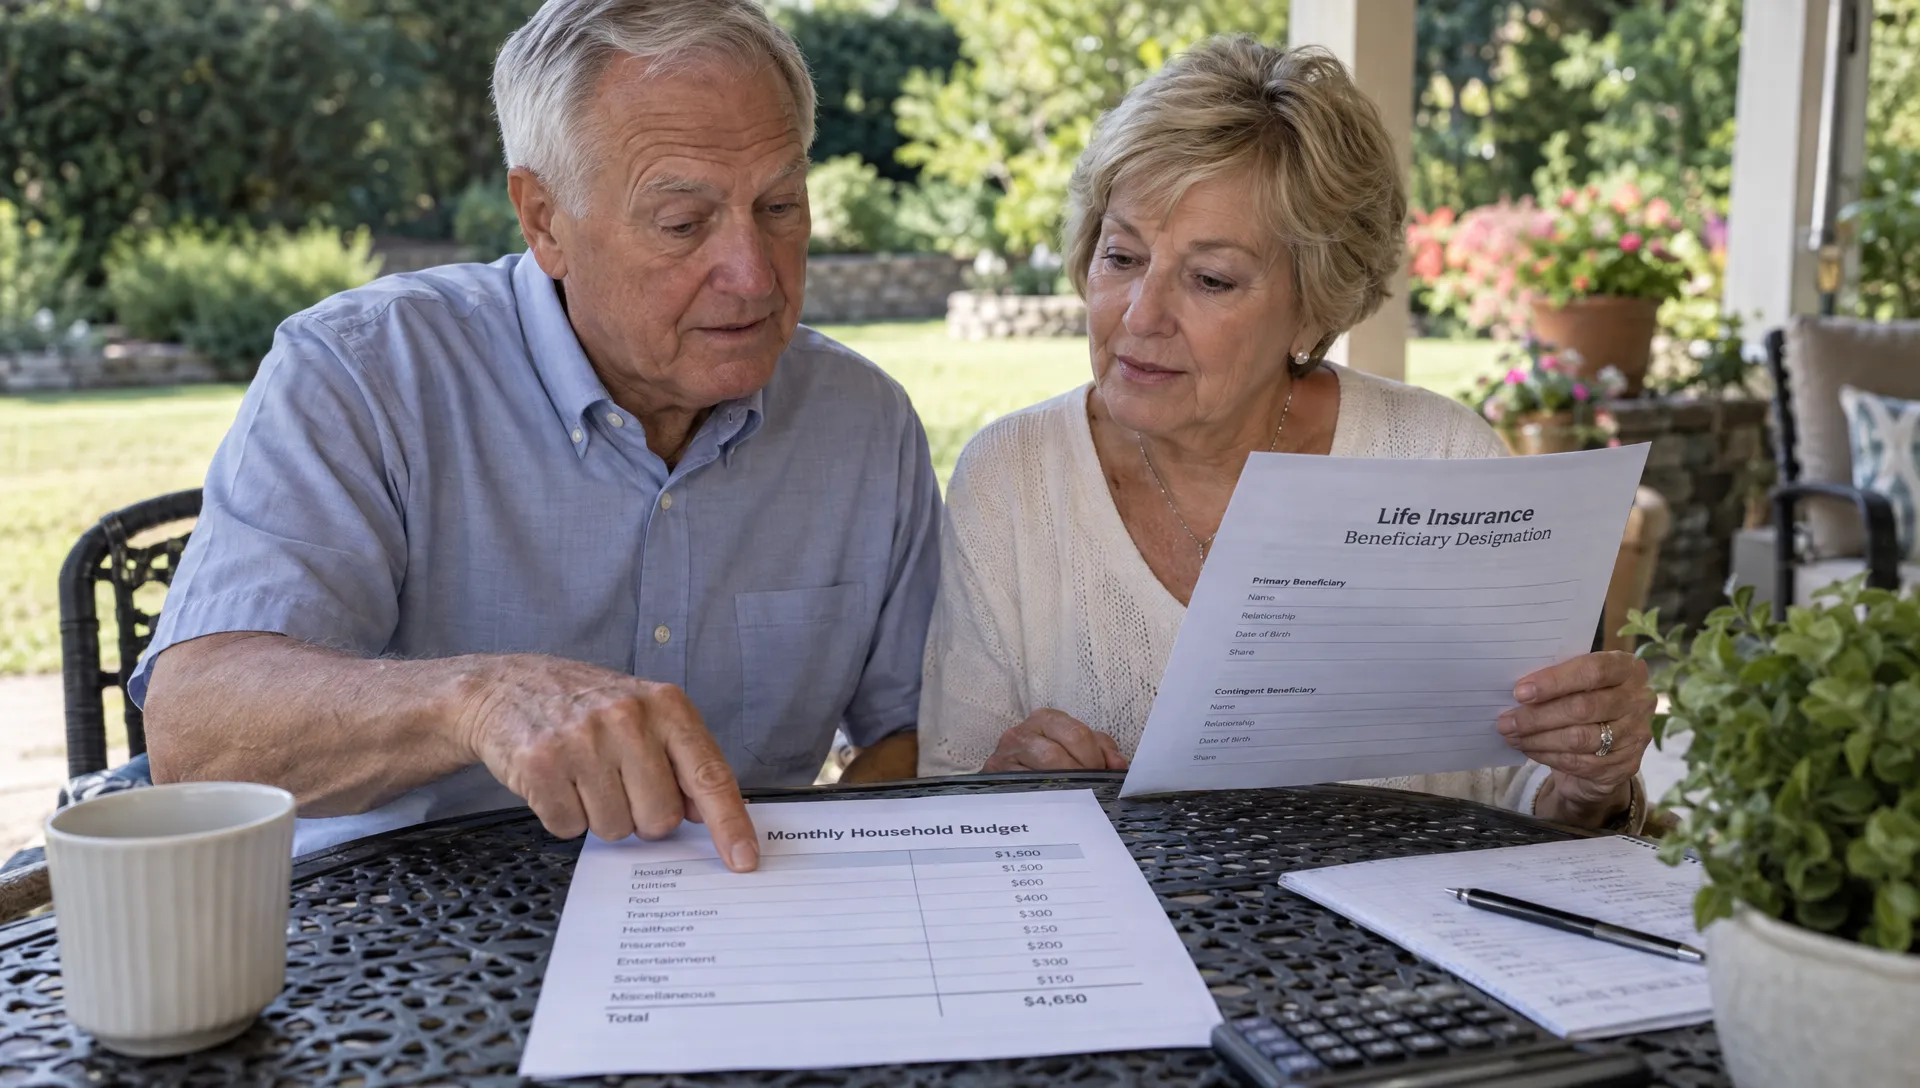
Beneficiary designations usually govern who receives policy proceeds, rather than instructions in your will. Review primary and contingent beneficiaries after a marriage, divorce or death, and ask an attorney about arrangements involving minors or someone receiving means-tested benefits.
Coordinating Medicare and life insurance also means keeping policy ownership consistent with your broader financial plan. Ownership can affect estate-tax treatment, and naming an estate as beneficiary can change how proceeds are administered. Neither decision should be made solely to simplify paperwork.
If you are coordinating a policy with estate documents in New York or Connecticut, discussing wills and estates with Clair Gjertsen Weathers PLLC can help you review how those decisions fit together. Questions about Medicaid eligibility also require advice specific to the applicable program and state.
Coordinate Medicare with other health coverage separately
Life insurance does not participate in the health insurance billing order. Employer health insurance, retiree coverage and Medicare can, so verify which health plan pays first before making enrollment decisions.
For someone eligible for Medicare because of age, coverage through current employment generally pays first when the employer has 20 or more employees. With a smaller employer, Medicare generally pays first. Exceptions apply, including some multi-employer arrangements, and different rules can apply to disability or end-stage renal disease.
Retiree health coverage generally pays after Medicare. COBRA and retiree coverage also do not provide the same protection for delaying Part B enrollment that qualifying coverage based on current employment can provide. Ask the benefits administrator how the plan works with Medicare, then confirm the applicable rules using Medicare's guidance on who pays first.
Reviewing Medicare and life insurance together is sensible for budgeting, but their enrollment decisions remain separate. Ending employer life coverage does not determine when you should enroll in Part B, and buying life insurance does not prevent Medicare enrollment penalties.
For a broader explanation of health plan choices, Insurance2All's guide to finding the right senior health coverage covers Original Medicare, Medicare Advantage, Medigap and Part D.
Protect your healthcare budget before adding coverage
A life policy should not crowd out essential medical coverage or leave you unable to afford prescriptions and routine expenses. Compare the total retirement budget, not just two monthly premiums.
Original Medicare has no annual out-of-pocket maximum for Part A and Part B services. Medicare Advantage plans have an annual limit for covered Part A and Part B services, but that limit does not include every healthcare expense. Drug costs, noncovered services and plan rules still matter.
Neither ordinary life insurance nor Medicare is a complete long-term care funding plan. Medicare.gov explains that Medicare does not cover most long-term custodial care. Some life policies offer living-benefit or long-term care riders, but eligibility, charges and benefit reductions depend on the contract. Do not assume an existing policy includes them.
Before changing Medicare and life insurance arrangements, gather four items:
- Current coverage details: Include health plan documents, life policy statements and employer benefit notices.
- A survivor budget: Estimate income and expenses after either spouse or partner dies.
- Policy continuation terms: Check expiration dates, conversion deadlines, surrender charges and outstanding loans.
- An affordable premium limit: Preserve money for healthcare, housing and emergency reserves.
Do not cancel an existing life policy until any replacement has been approved, issued and confirmed in force. A new application may be declined or cost more than expected.
Frequently asked questions
Does Medicare pay a death benefit to my family? No. Medicare is health insurance and does not provide a life insurance death benefit. Eligible hospice care is a healthcare benefit, not a payment to survivors for funeral costs or lost income.
Do I have to buy life insurance when I enroll in Medicare? No. There is no requirement to purchase Medicare and life insurance together. Buy life insurance only if its benefit addresses a financial need or a deliberate legacy goal at a sustainable cost.
Can I keep life insurance after age 65? Often, yes, but the policy controls. Term coverage may expire at the end of its term, employer coverage may change at retirement and permanent insurance requires sufficient funding under its terms. Review the contract rather than assuming age 65 ends coverage.
Can I use a life policy's cash value to pay Medicare premiums? Depending on the contract, withdrawals, loans or surrender may provide funds. Those choices can reduce the death benefit, create charges or tax consequences, or increase lapse risk. Ask the insurer for an in-force illustration or other policy-specific information before acting.
Does Medicare's annual enrollment period apply to life insurance? No. The October 15 through December 7 Medicare enrollment period allows certain Medicare health and drug plan changes. It is not a life insurance enrollment window or a universal opportunity to buy Medigap without medical underwriting.
Compare coverage against your actual retirement needs
The practical goal is to use Medicare and life insurance for the risks each addresses, without paying for unnecessary protection. Start with your healthcare coverage, calculate any survivor shortfall and review policies you already own.
Insurance2All offers free, no-commitment comparisons across more than 50 carriers, with licensed advisor guidance, bilingual support and enrollment application assistance. Compare available options against your budget and family needs before deciding what to keep, change or add.